


Dear Dad,
Anthropic goes public tomorrow at ~$85/share at $1.54T market cap. You asked me if you should invest.
I’ve been investing for over 10 years, beginning my career as a software VC at Insight Partners and most recently as a public / privates investor at Whale Rock.
I even built a two financials model on Anthropic that went viral on Twitter on Anthropic at $1T ARR in 2030 and Anthropic at $800B ARR in 2030 after AI fear.
In my 10 years, there’s no company like Anthropic. It’s not only the fastest growing company ever…
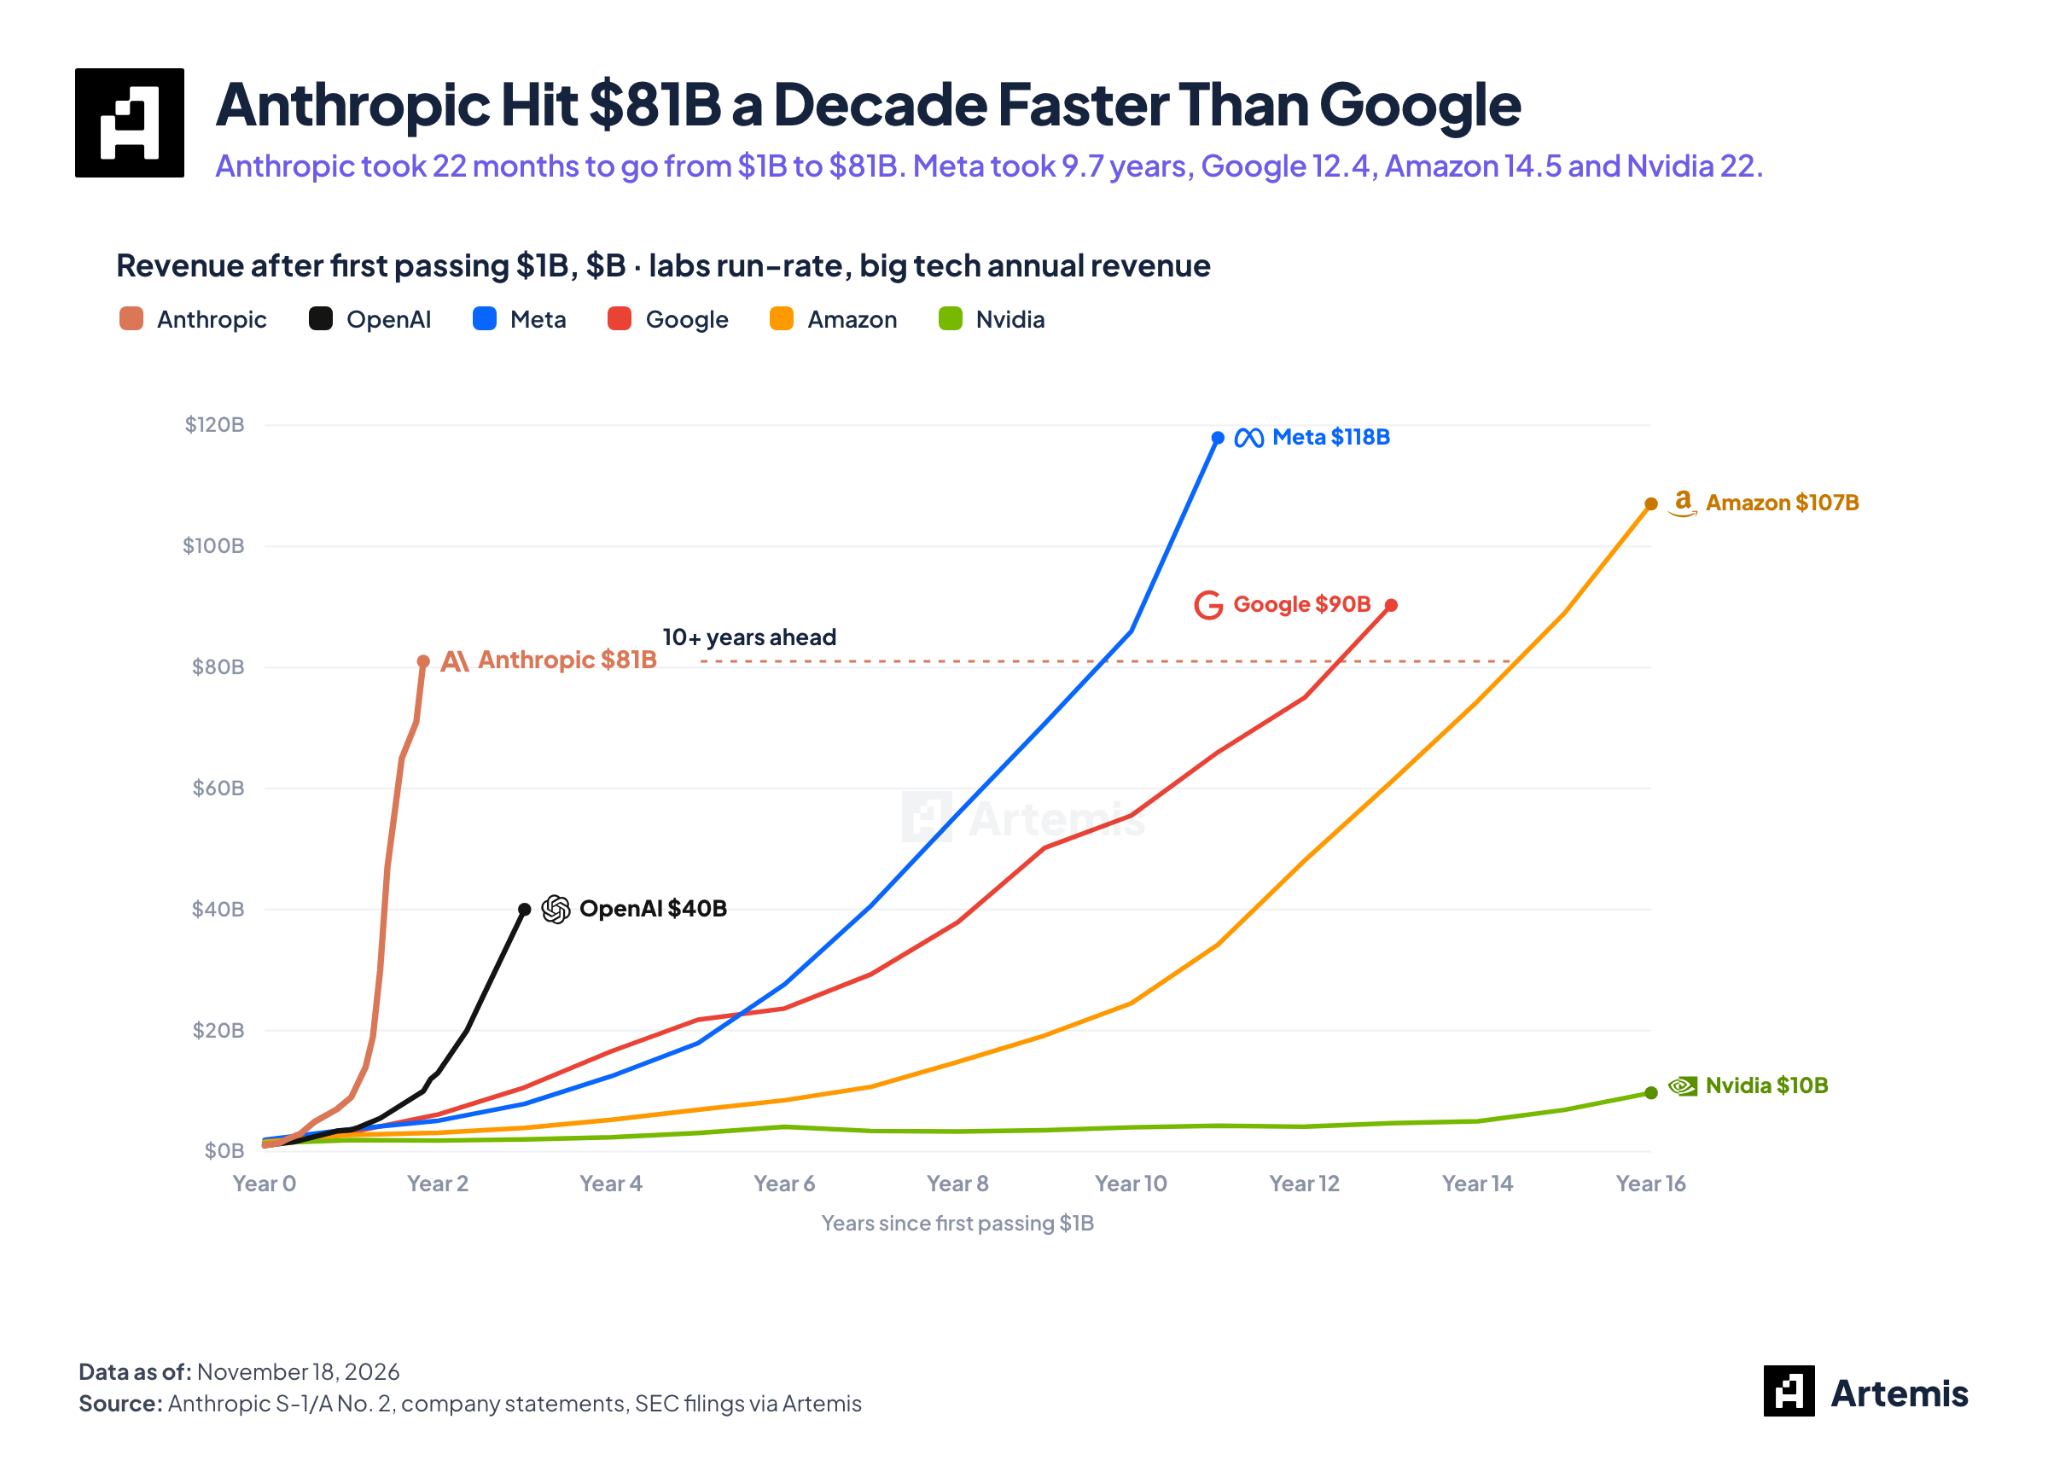
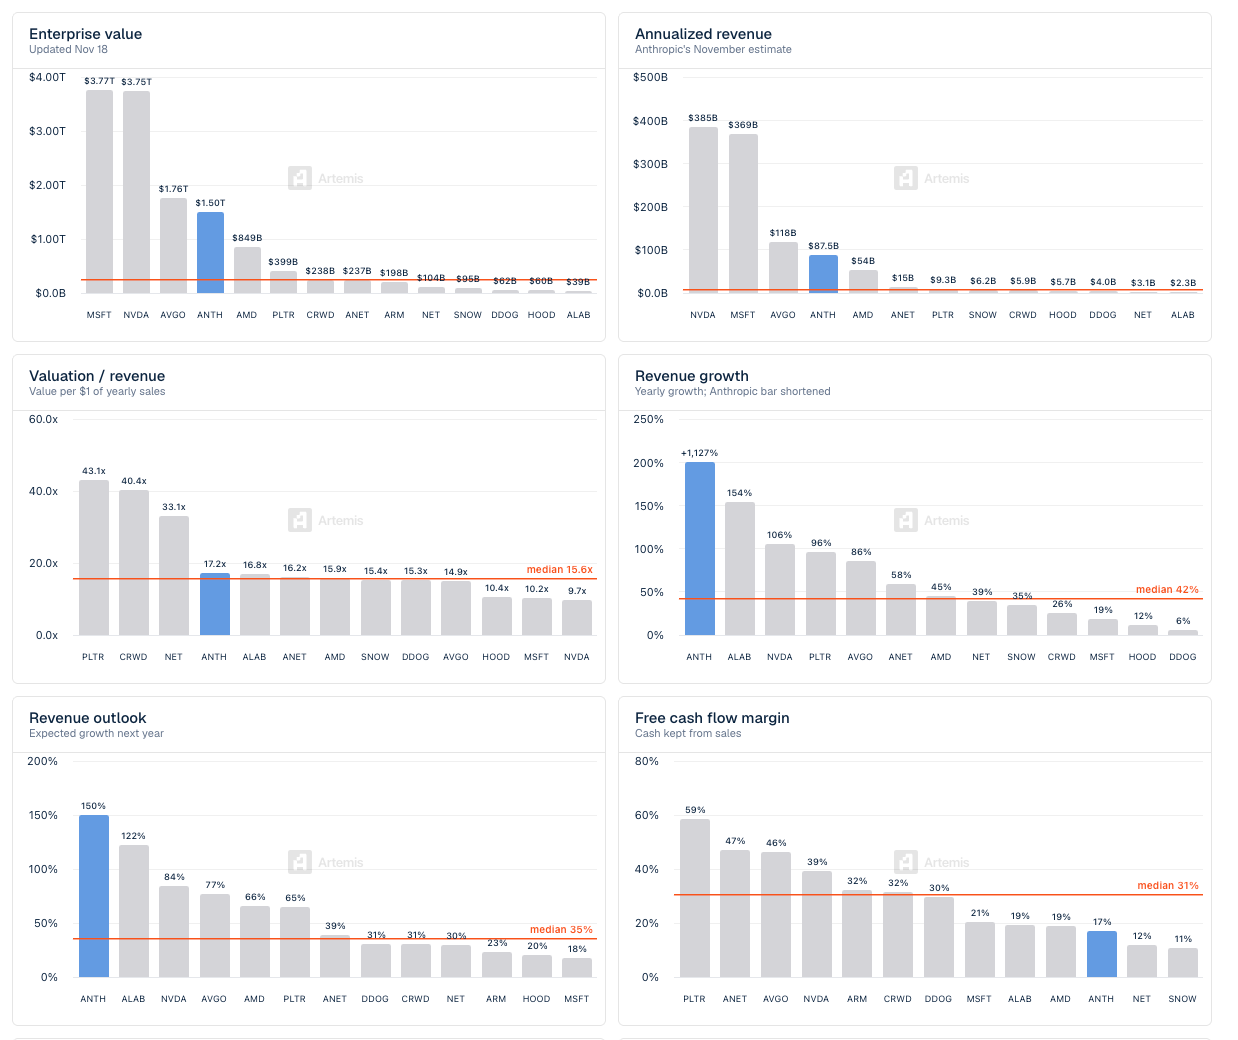
…but the first time there’s a public company that’s growing 10x (fastest in the public markets) and got to $80B ARR on just one vertical (coding agents) and is STILL a moonshot bet that still has a 10x upside at IPO.
The wackiest part is the co-founders Dario, Danielle and team. I’ve realized the Anthropic cofounders are MORE driven by their mission of making AI systems aligned with human values than making money.
Their effective altruist roots and mission oriented approach will make Anthropic the most valuable company in the world and safer as a result.
Here’s my thesis for why Anthropic becomes a $10T company in the next 4 years*
Except if Anthropic goes public beyond $3T or prices beyond $160/share day 1.
Thesis: the first $10T company
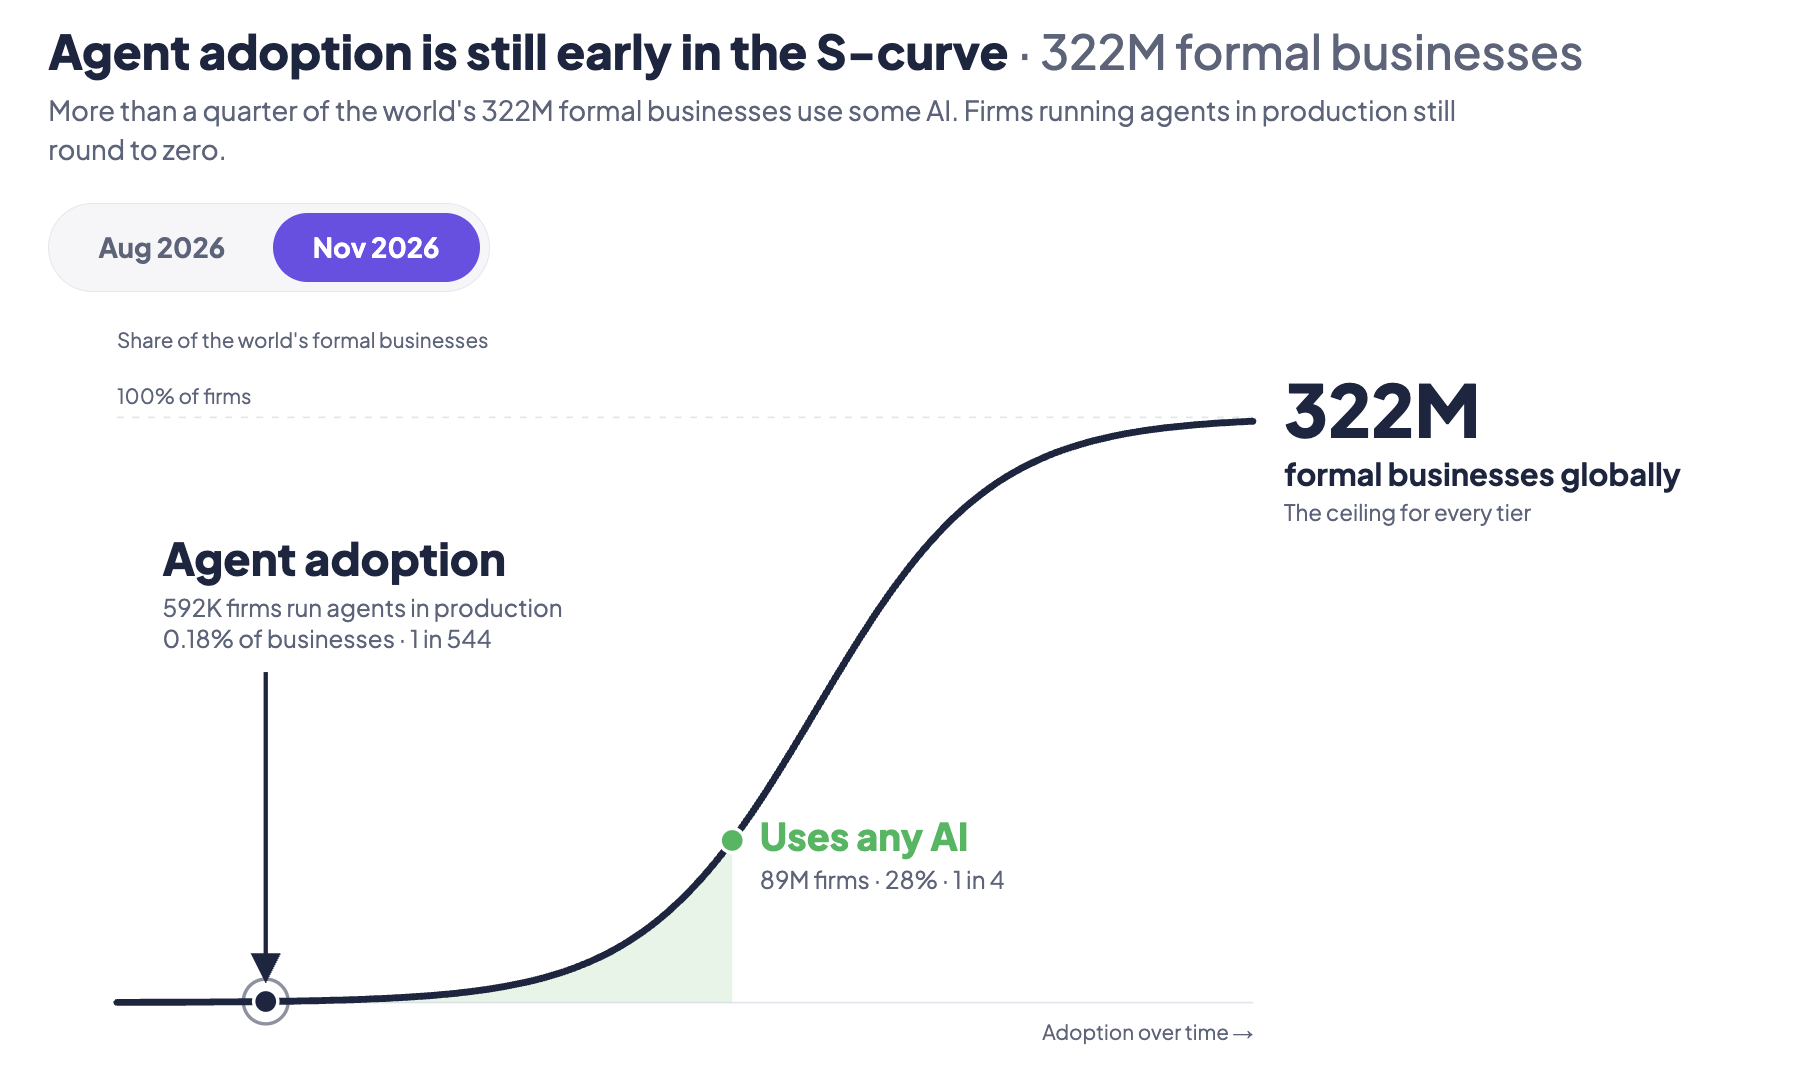
Alex Sacerdote at Whale Rock taught us to look for ideas early on the S-curve.
Agents are DEFINITIONALLY early on the adoption curve in companies ACTUALLY replacing workers.
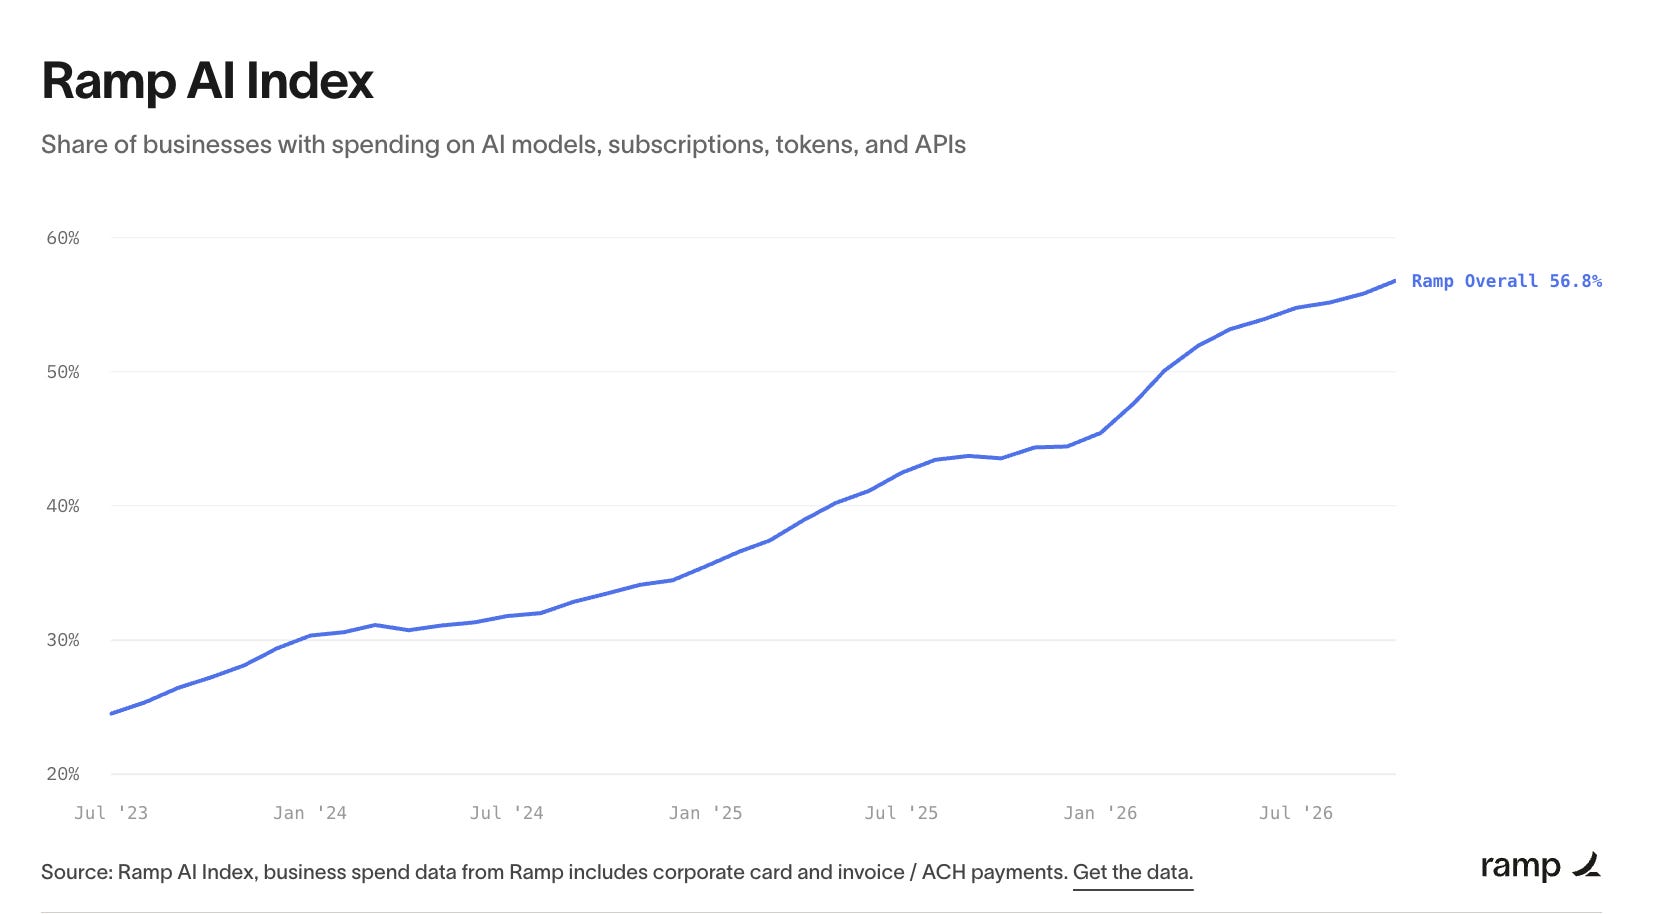
Yes, most businesses in the U.S on Ramp pay for some AI (56.8% as of Oct ‘26) but on average they spend $15/month which is the equivalent of the Claude Pro plan
In January 2026 of this year, I started using Claude Code at Artemis and as a non-technical CEO, for the first time… I was able to use agents to ship products end to end simply just typing what I want to build.
I rebuilt my last startup Public Comps that took many years to build in minutes.
At Artemis we went from 25 full-time employees to 8 employees and we’re shipping FASTER with coding agents from Claude Code / Codex / Devin.
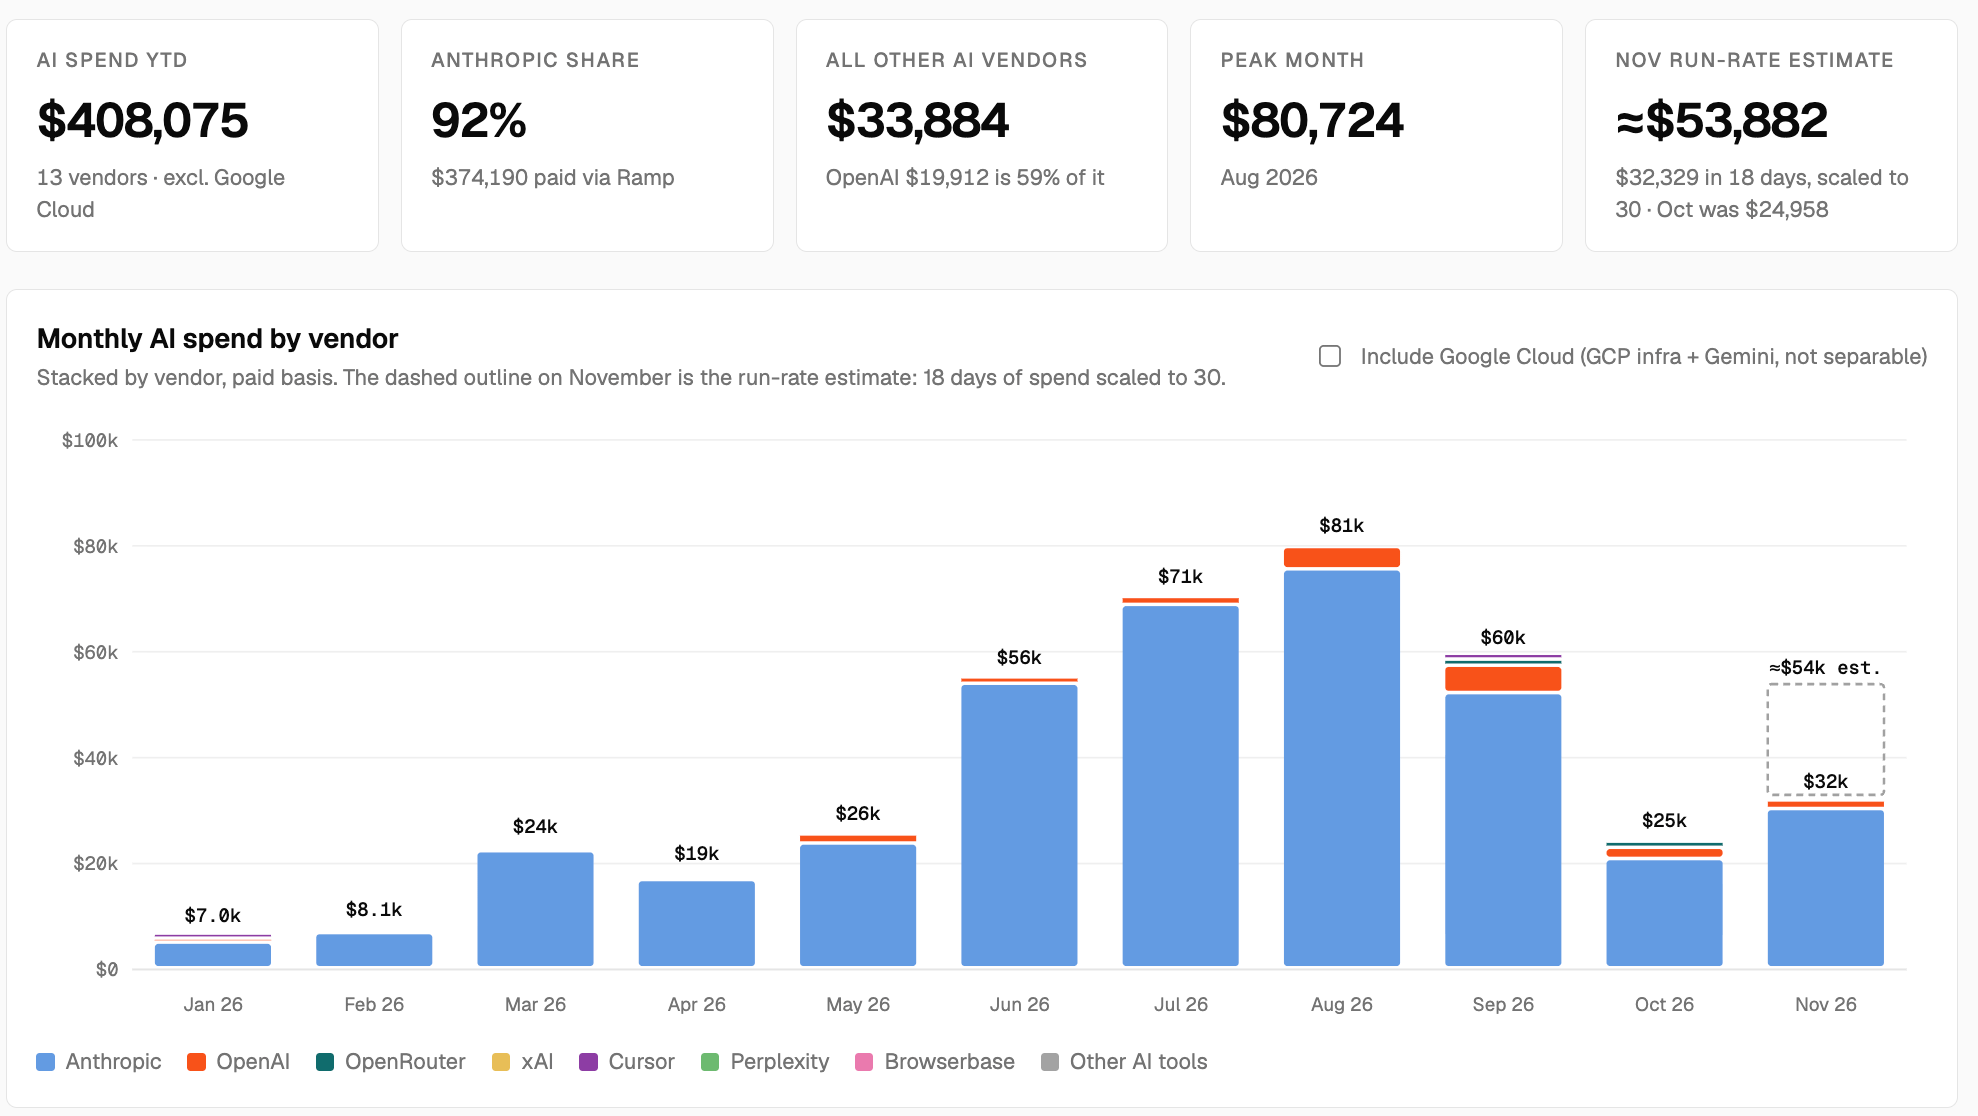
We spent $400K in tokens this year and 92% of the spend was on Anthropic. Most businesses will look like Artemis in 2030 where businesses will spend on tokens instead of headcount.
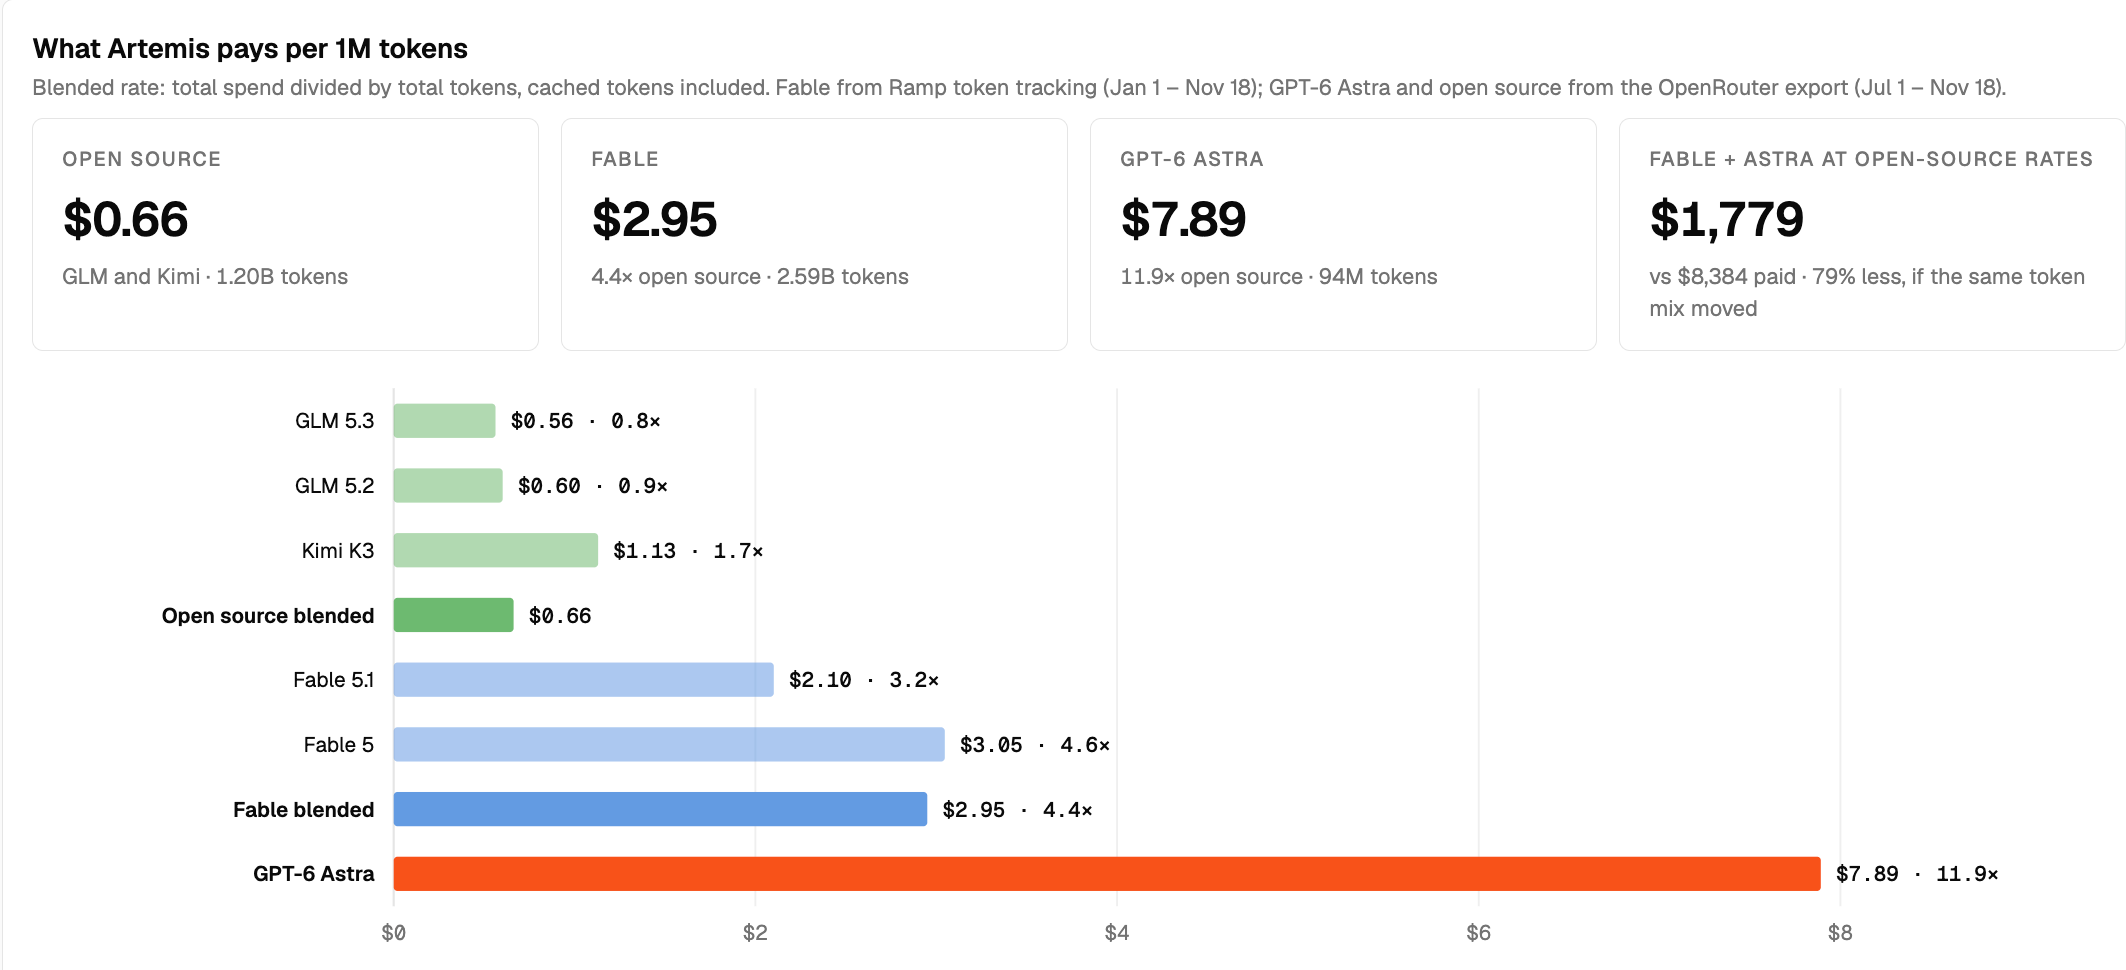
And we’ve experimented and used open source models like GLM and Kimi but consistently pay for Anthropic / OpenAI models that are 5-10x more expensive because the frontier models are just better at engineering / finance tasks.
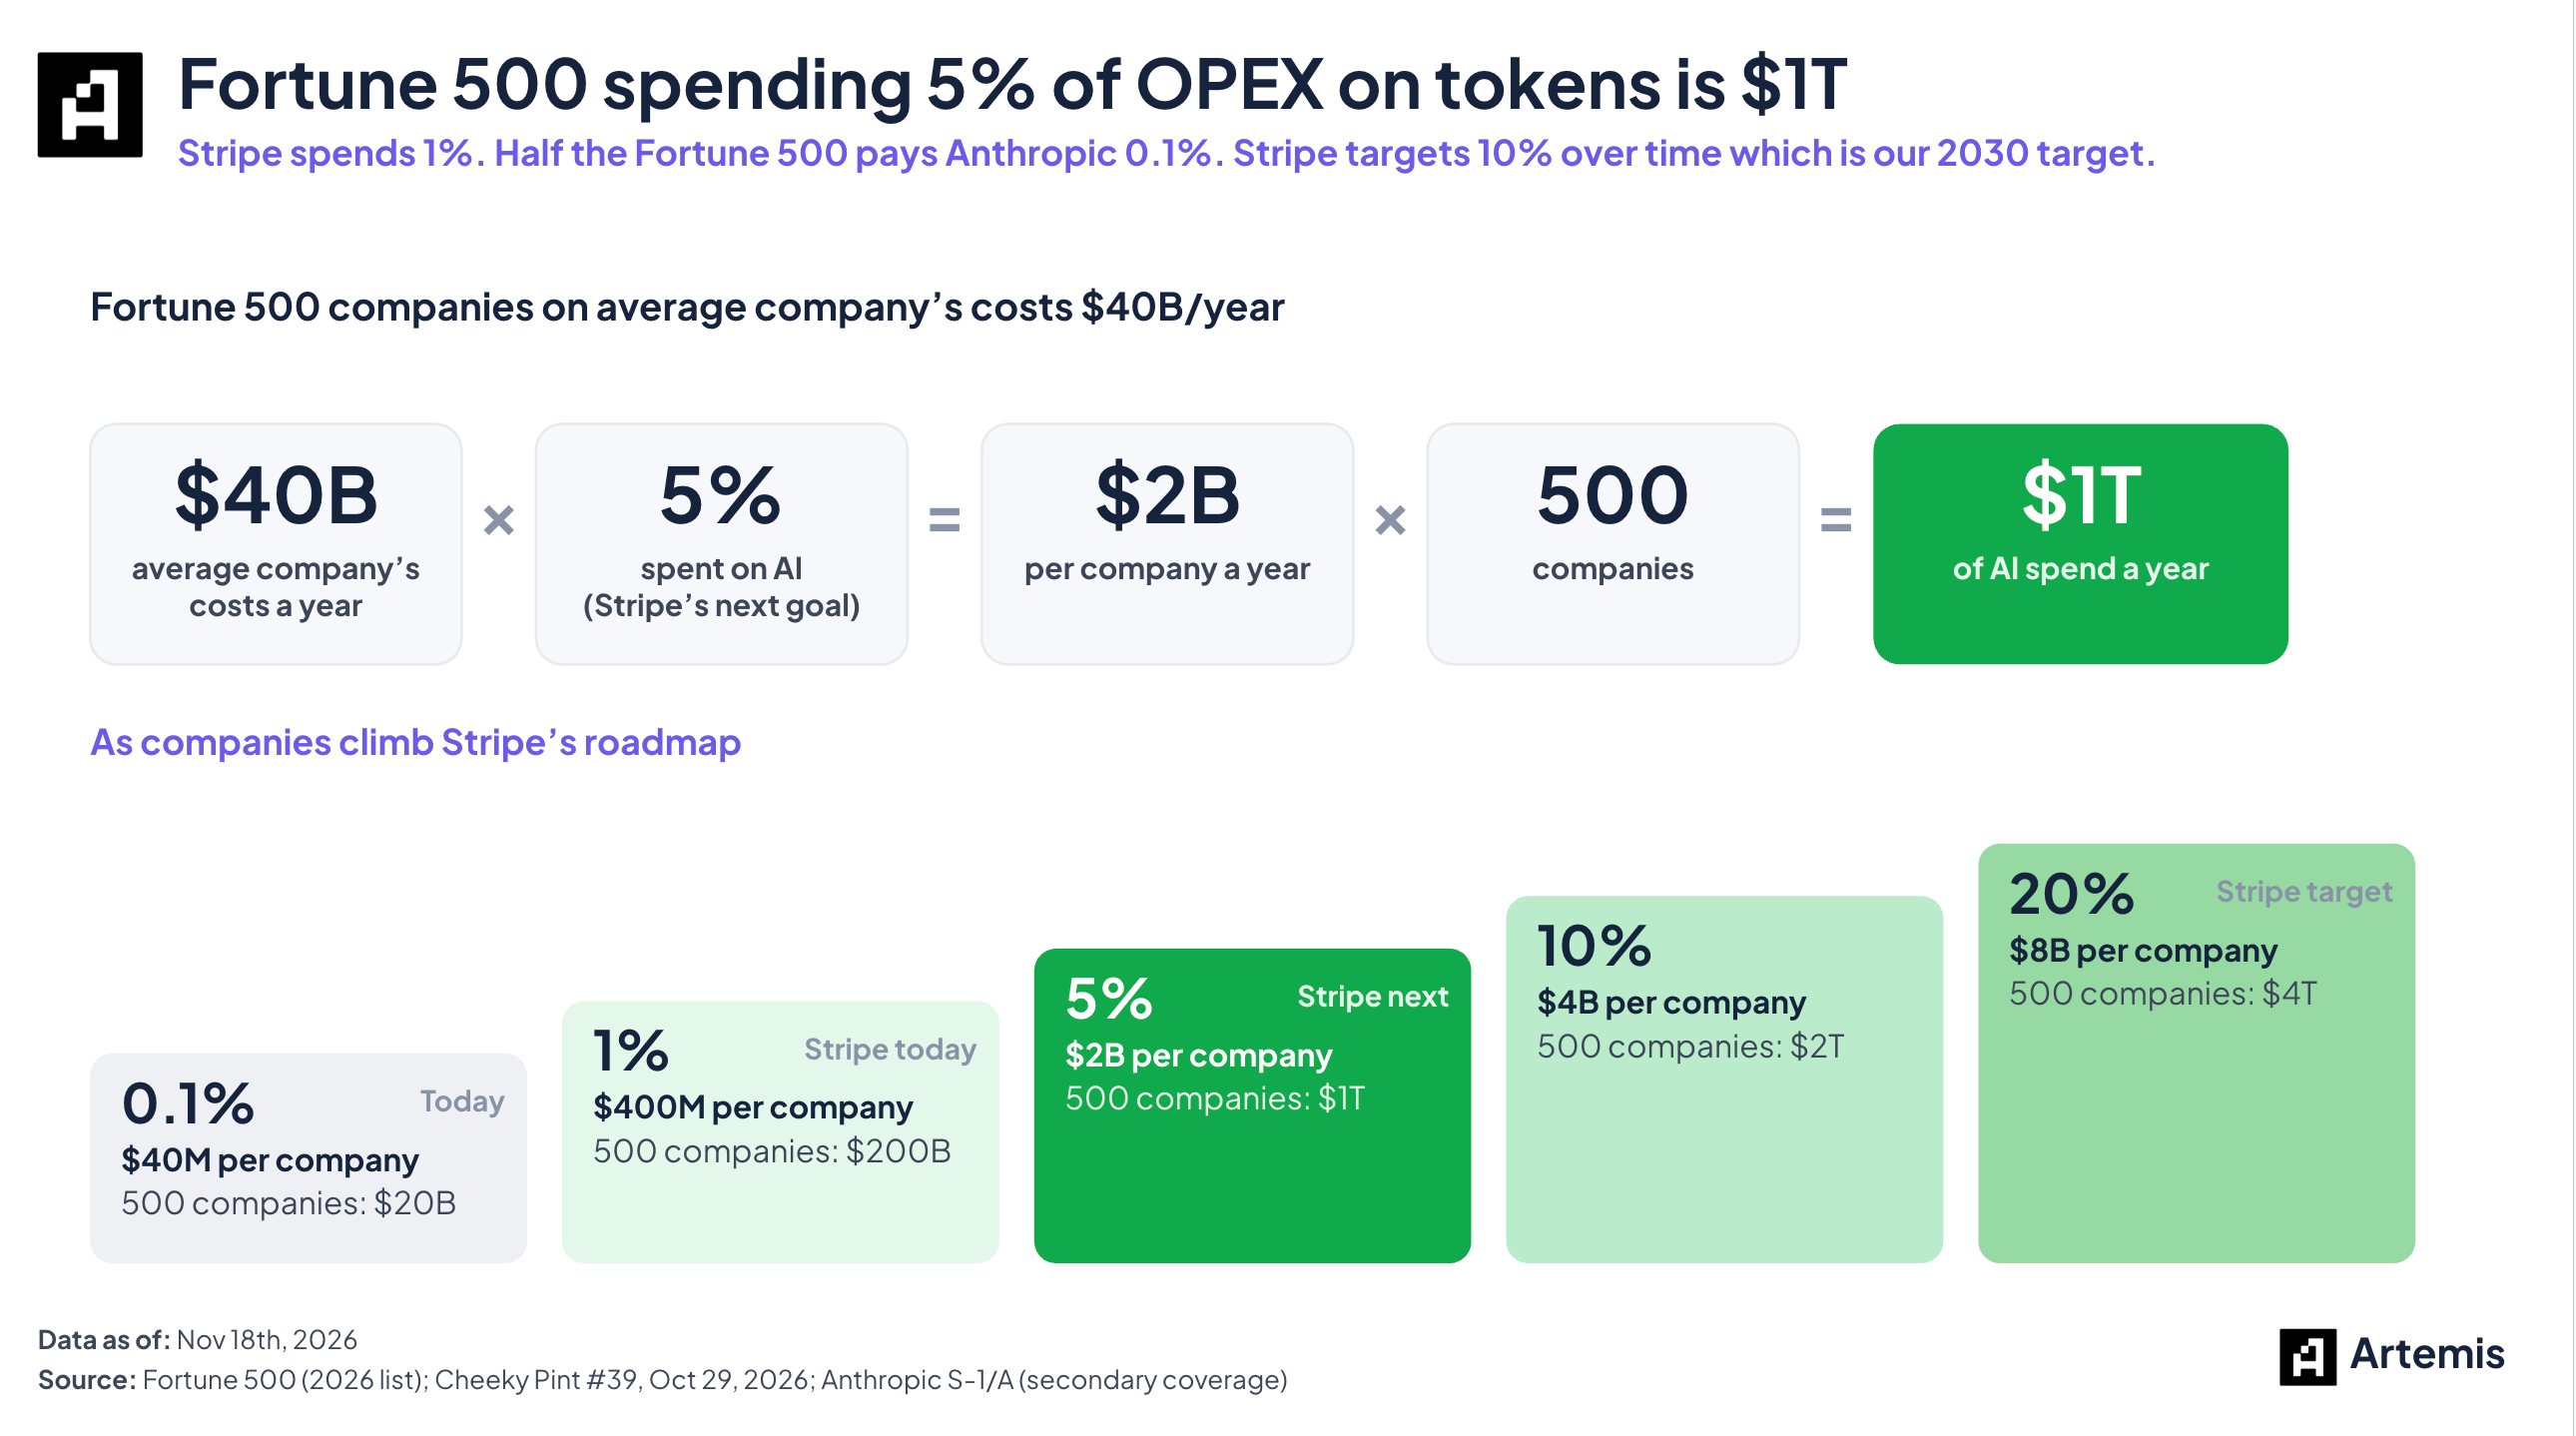
How to get to $800B ARR with Fortune 500
Anthropic got to $81B ARR primarily from coding (!) and that’s still just Fortune 500 paying 0.1% of their annual budget on tokens. That path to 10x to $800B is simple.
Stripe (leading fintech company) spends 1% of their yearly budget on tokens and anticipates spending closer to 10% overtime. If Fortune 500 spend 5-10% of OPEX on tokens with Anthropic / OpenAI that’s nearly $1-2T of AI spend a year from JUST Fortune 500.
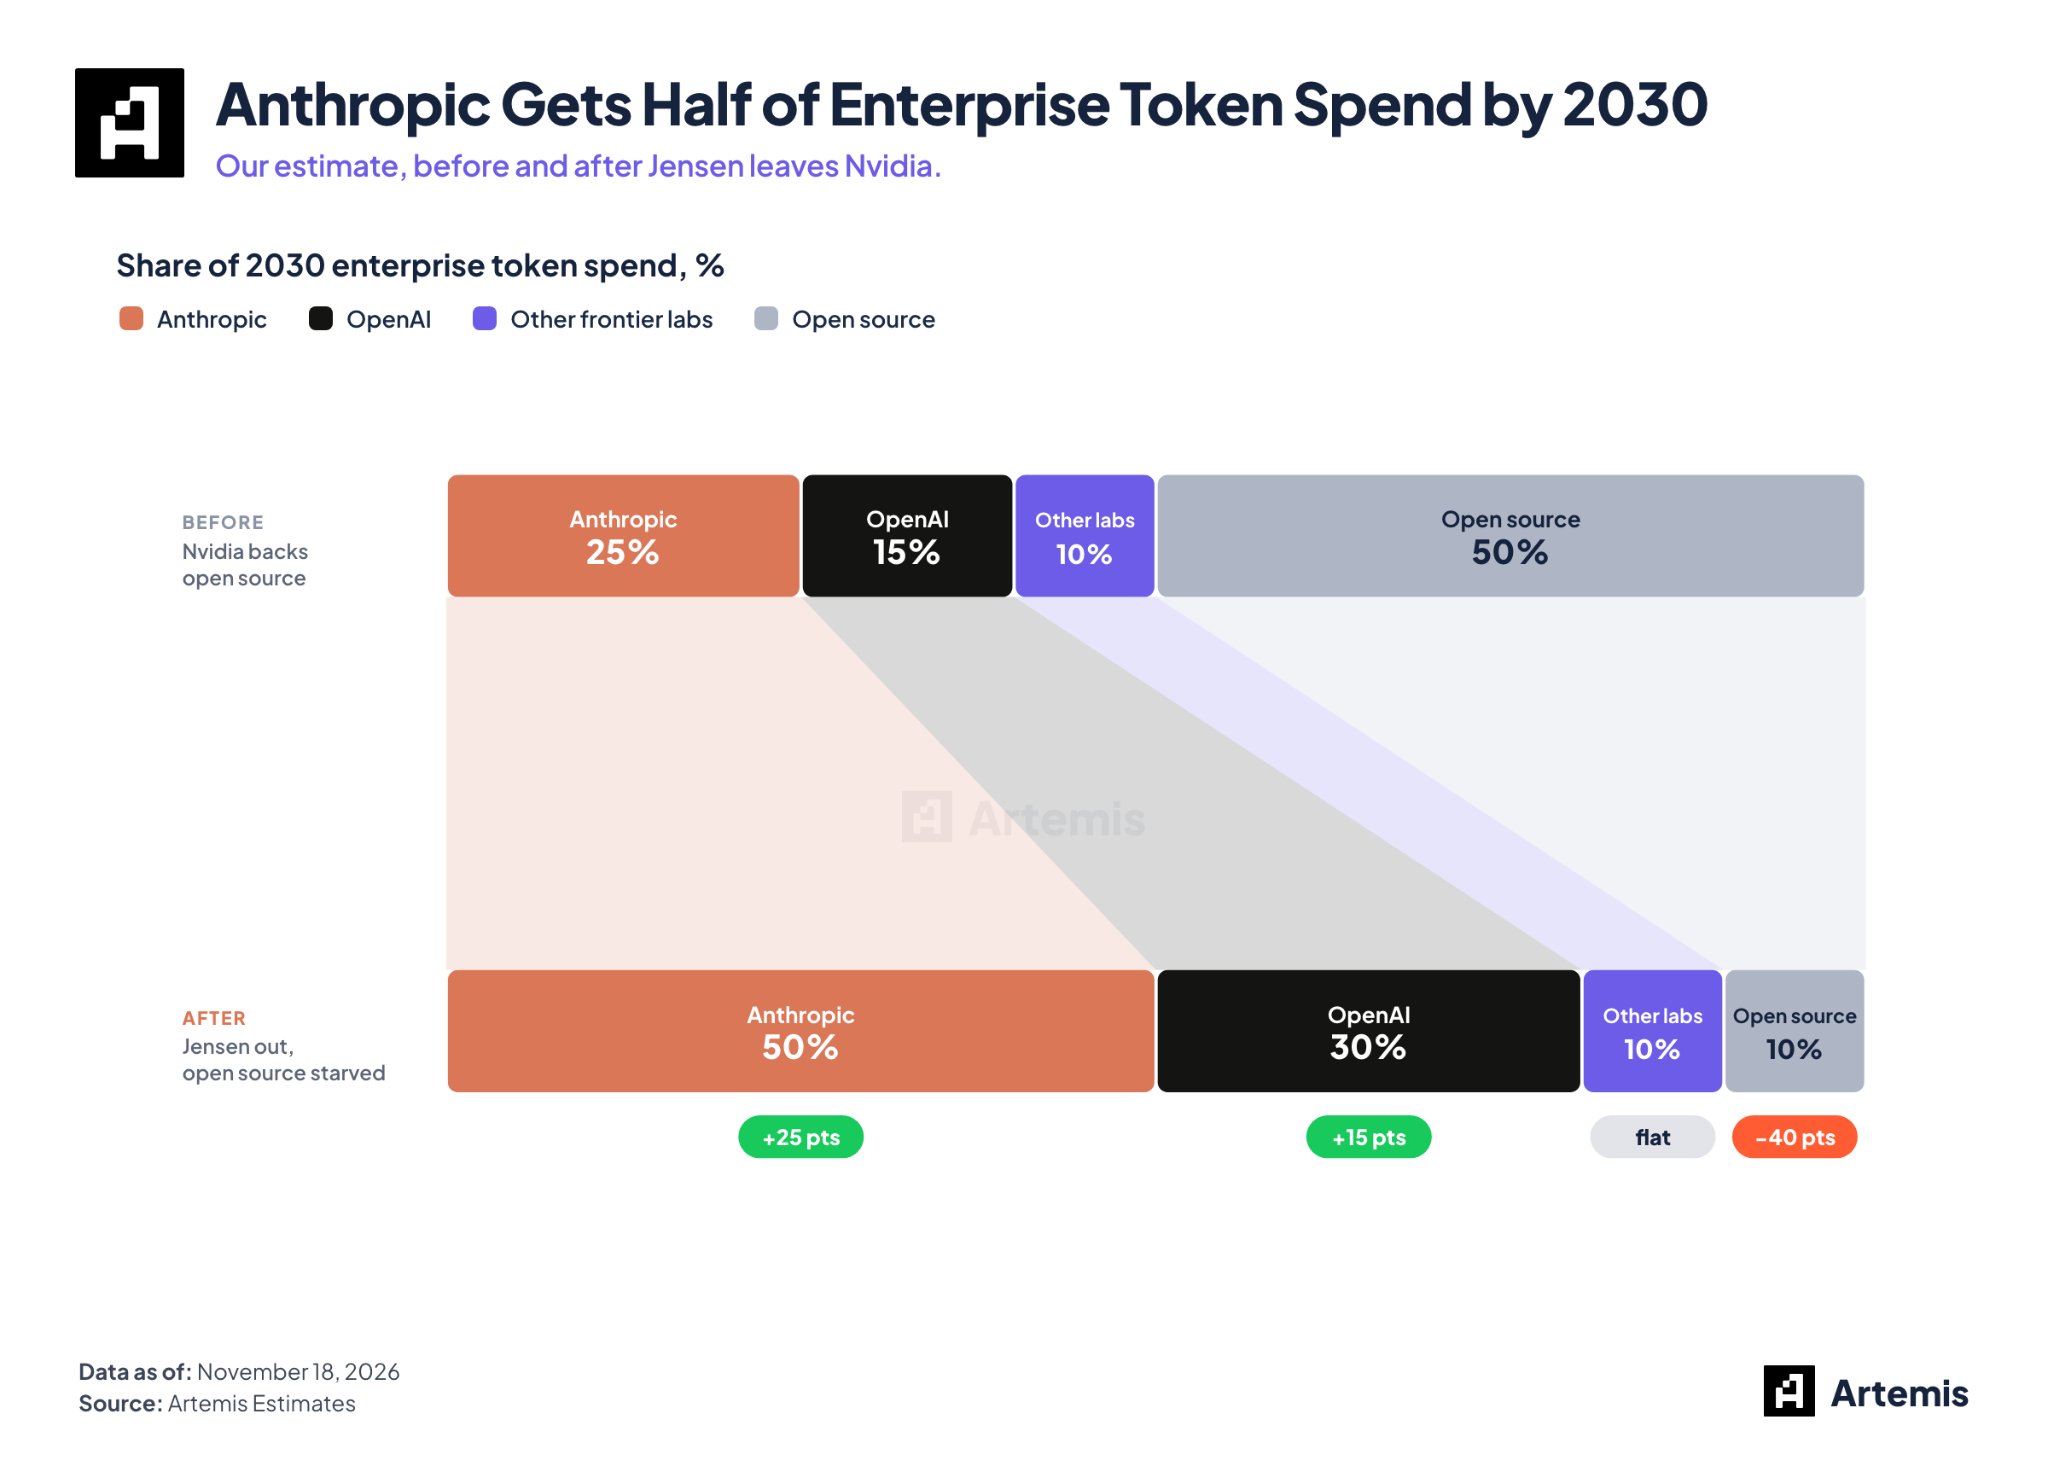
We believe with Jensen out at NVIDIA, there will be less competition to Anthropic through other American frontier labs that Nvidia backed or Chinese open source labs. With the threat of open source reduced, we believe at least HALF of all enterprise spend on AI will go towards Anthropic.
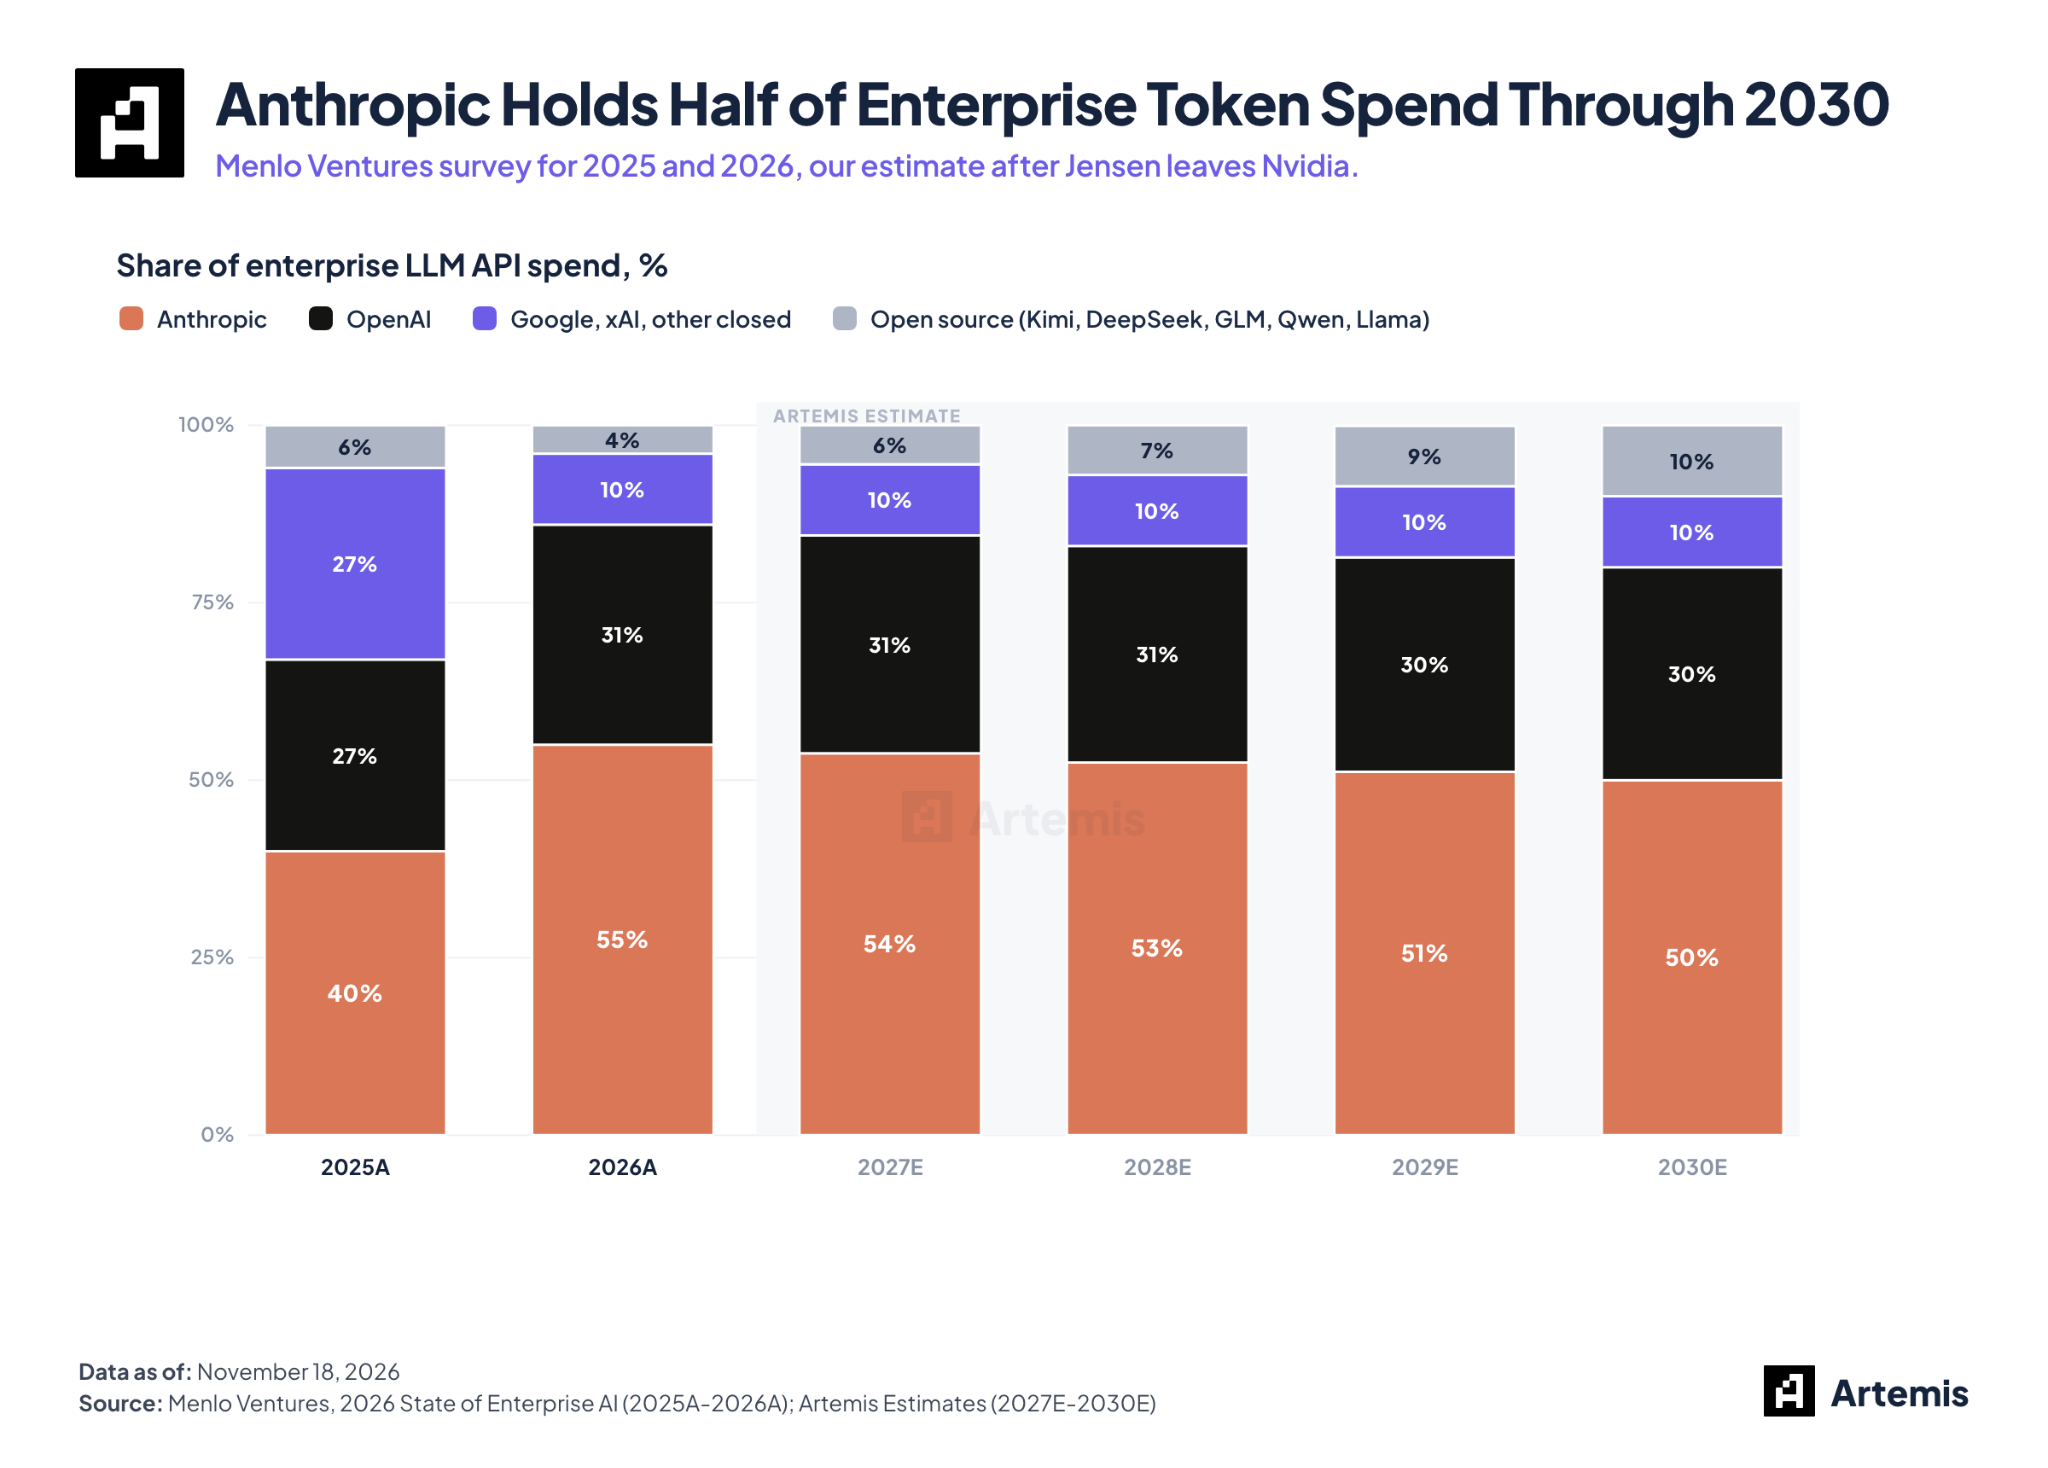
In short, Anthropic will be main provider of intelligence to the enterprise with >50% marketshare in 2030 of AI business spend. We think conservatively there’s at least $2T ARR spend in 2030 and that doesn’t even account for drug discovery if Anthropic figures out the cure for cancer and other new verticals we don’t even know about today or don’t show up in their financials just yet (e.g chip design).
With the threat of open source from Nvidia Nemos and GPUs to open source labs and a potentially weakened inference and neocloud market, Anthropic stands to benefit as both a frontier lab and primary way enterprises get inference WHILE gaining leverage over hyper scalers who are selling Anthropic tokens on their behalf (40%+ of revenue comes from AWS / GCP / Azure and a 10-15% take rate that might keep going down as they need Anthropic models to service their enterprises.)
The mission for Anthropic matters and is ignored by most investors: to create intelligence that aligns with human values. To get there Anthropic needs to have their models be the default choice for companies, governments such that it foreign hackers or terrorist or countries want to, say, create bio weapons or cyber security threats, Anthropic has the ability to intervene.
Comps: why Anthropic is … potentially cheap.
Generational businesses are always cheap in hindsight.
If Anthropic goes public $85/share that implies $1.5T, it’s actually cheap on a revenue basis compared to high flying public technology businesses.
Current comps (11/18) implies Anthropic will trade at 9.8x 2027 revenue, 5.0x 2028 revenue and 3.2x 2029 revenue (Artemis + Goldman + MBI estimates)
For the high growth software like Palantir, Cloudflare, Crowdstrike, they trade roughly from 27-33x 2027 revenue. 20-27x 2028 revenue and 10-18x 2029 revenue.
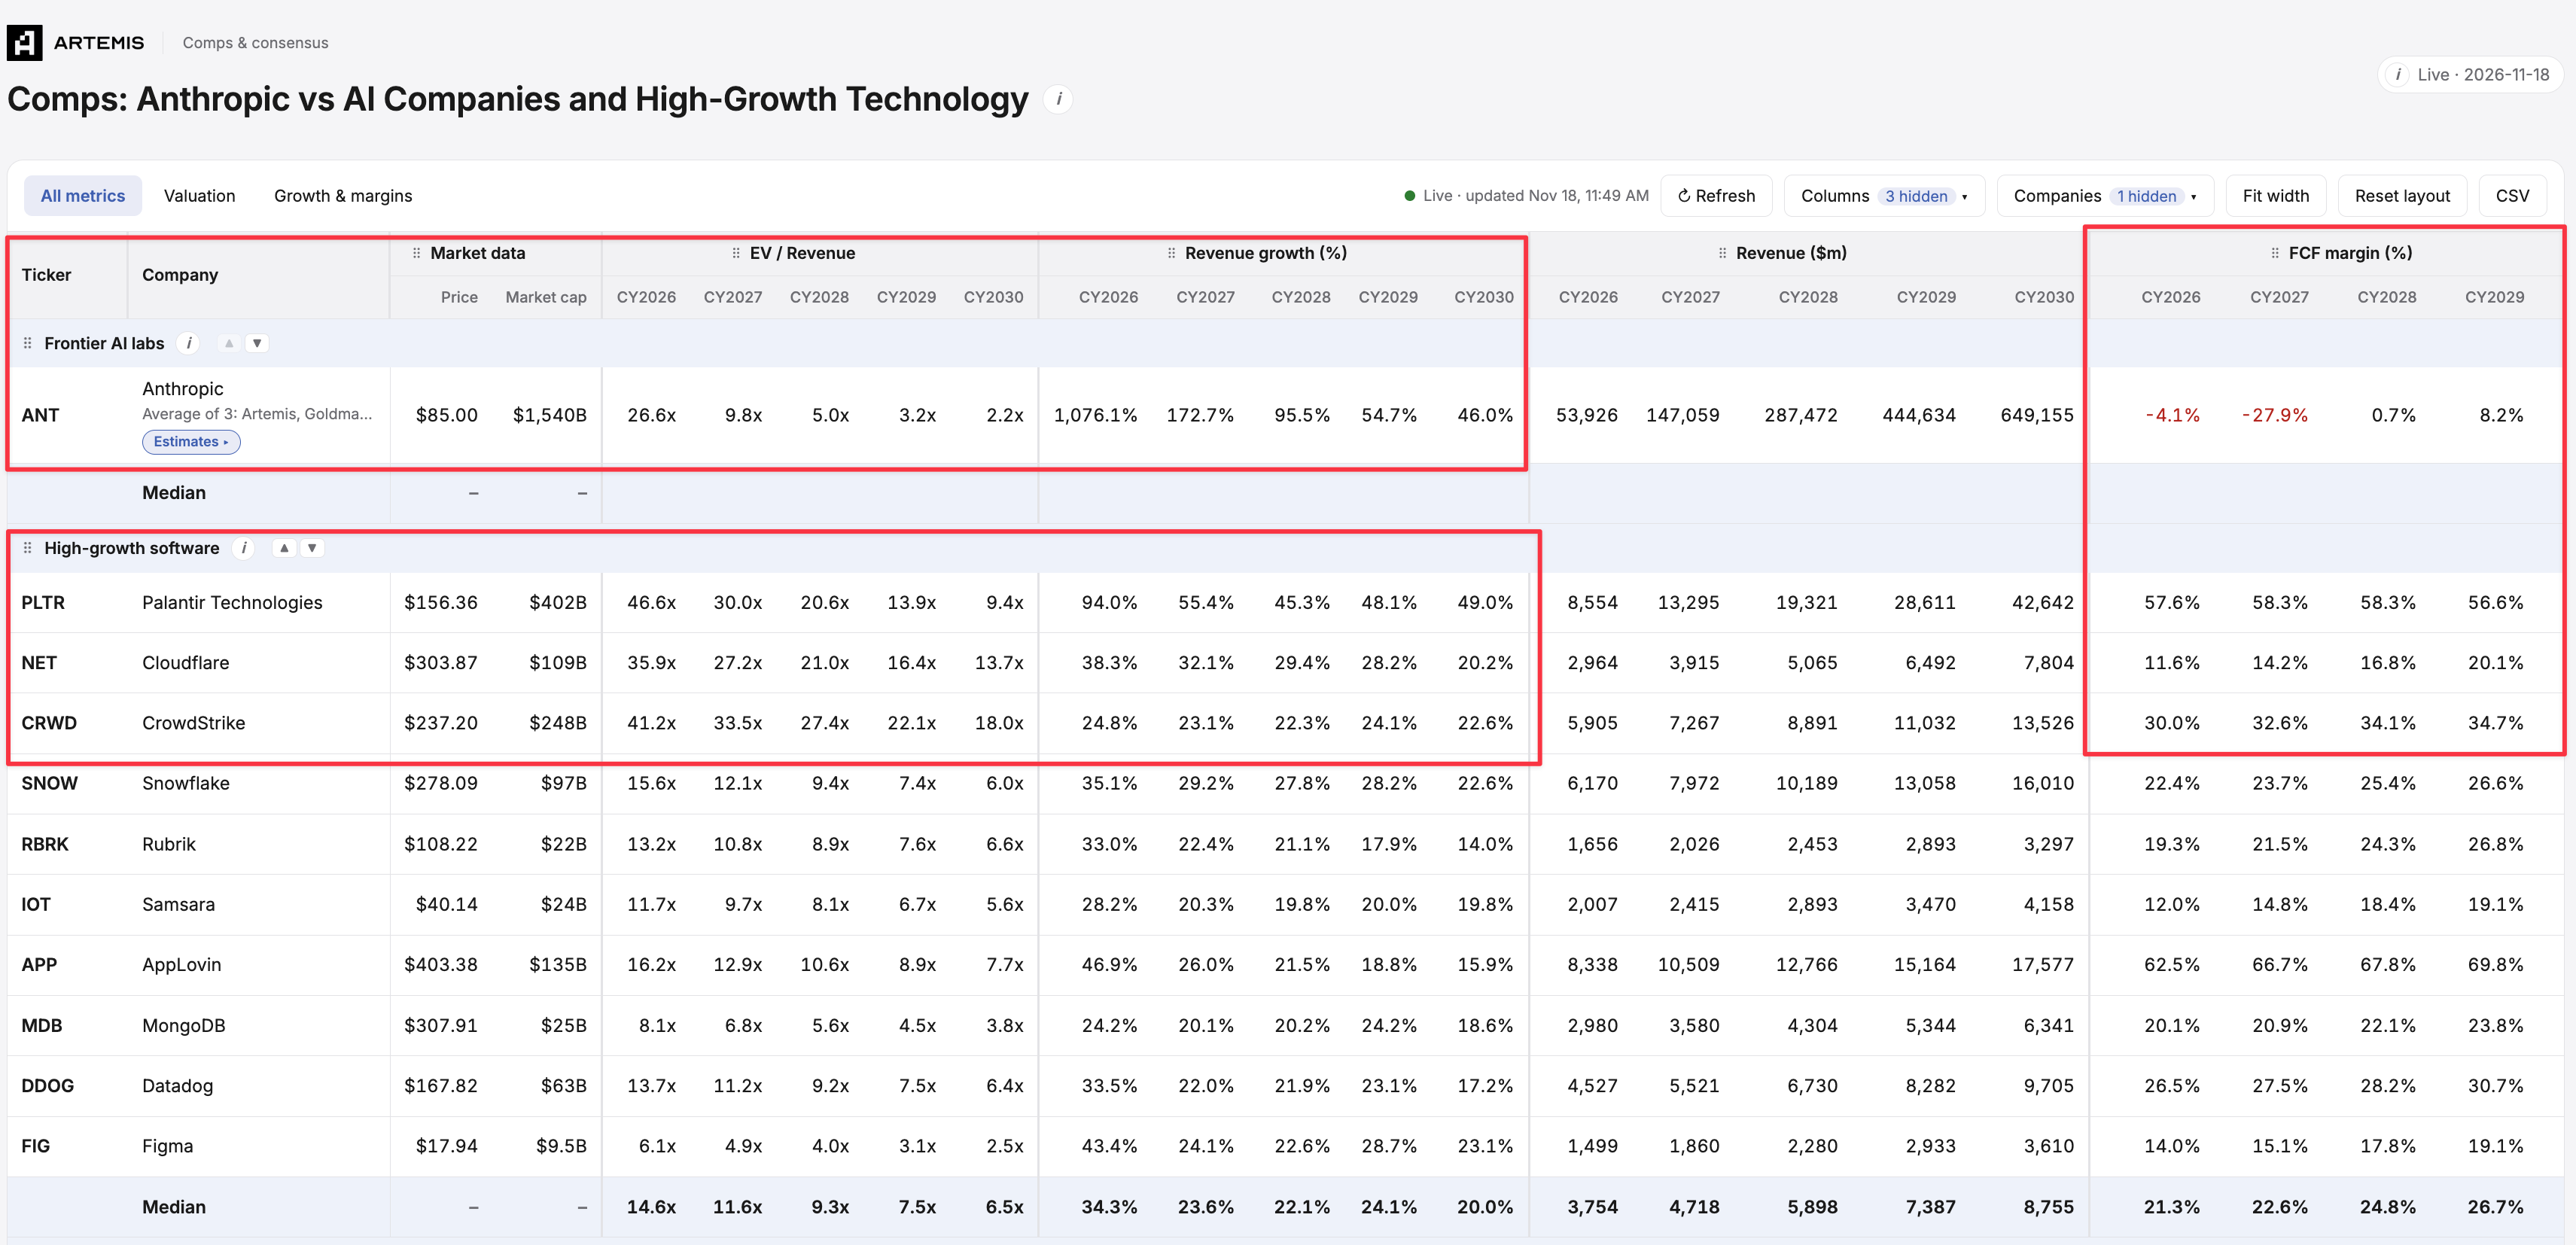
The difference is Anthropic will be burning a lot of cash in the next couple of years on Anthropic Direct and building out their own data centers before we start seeing Anthropic become free cash flow in 2029/2030.
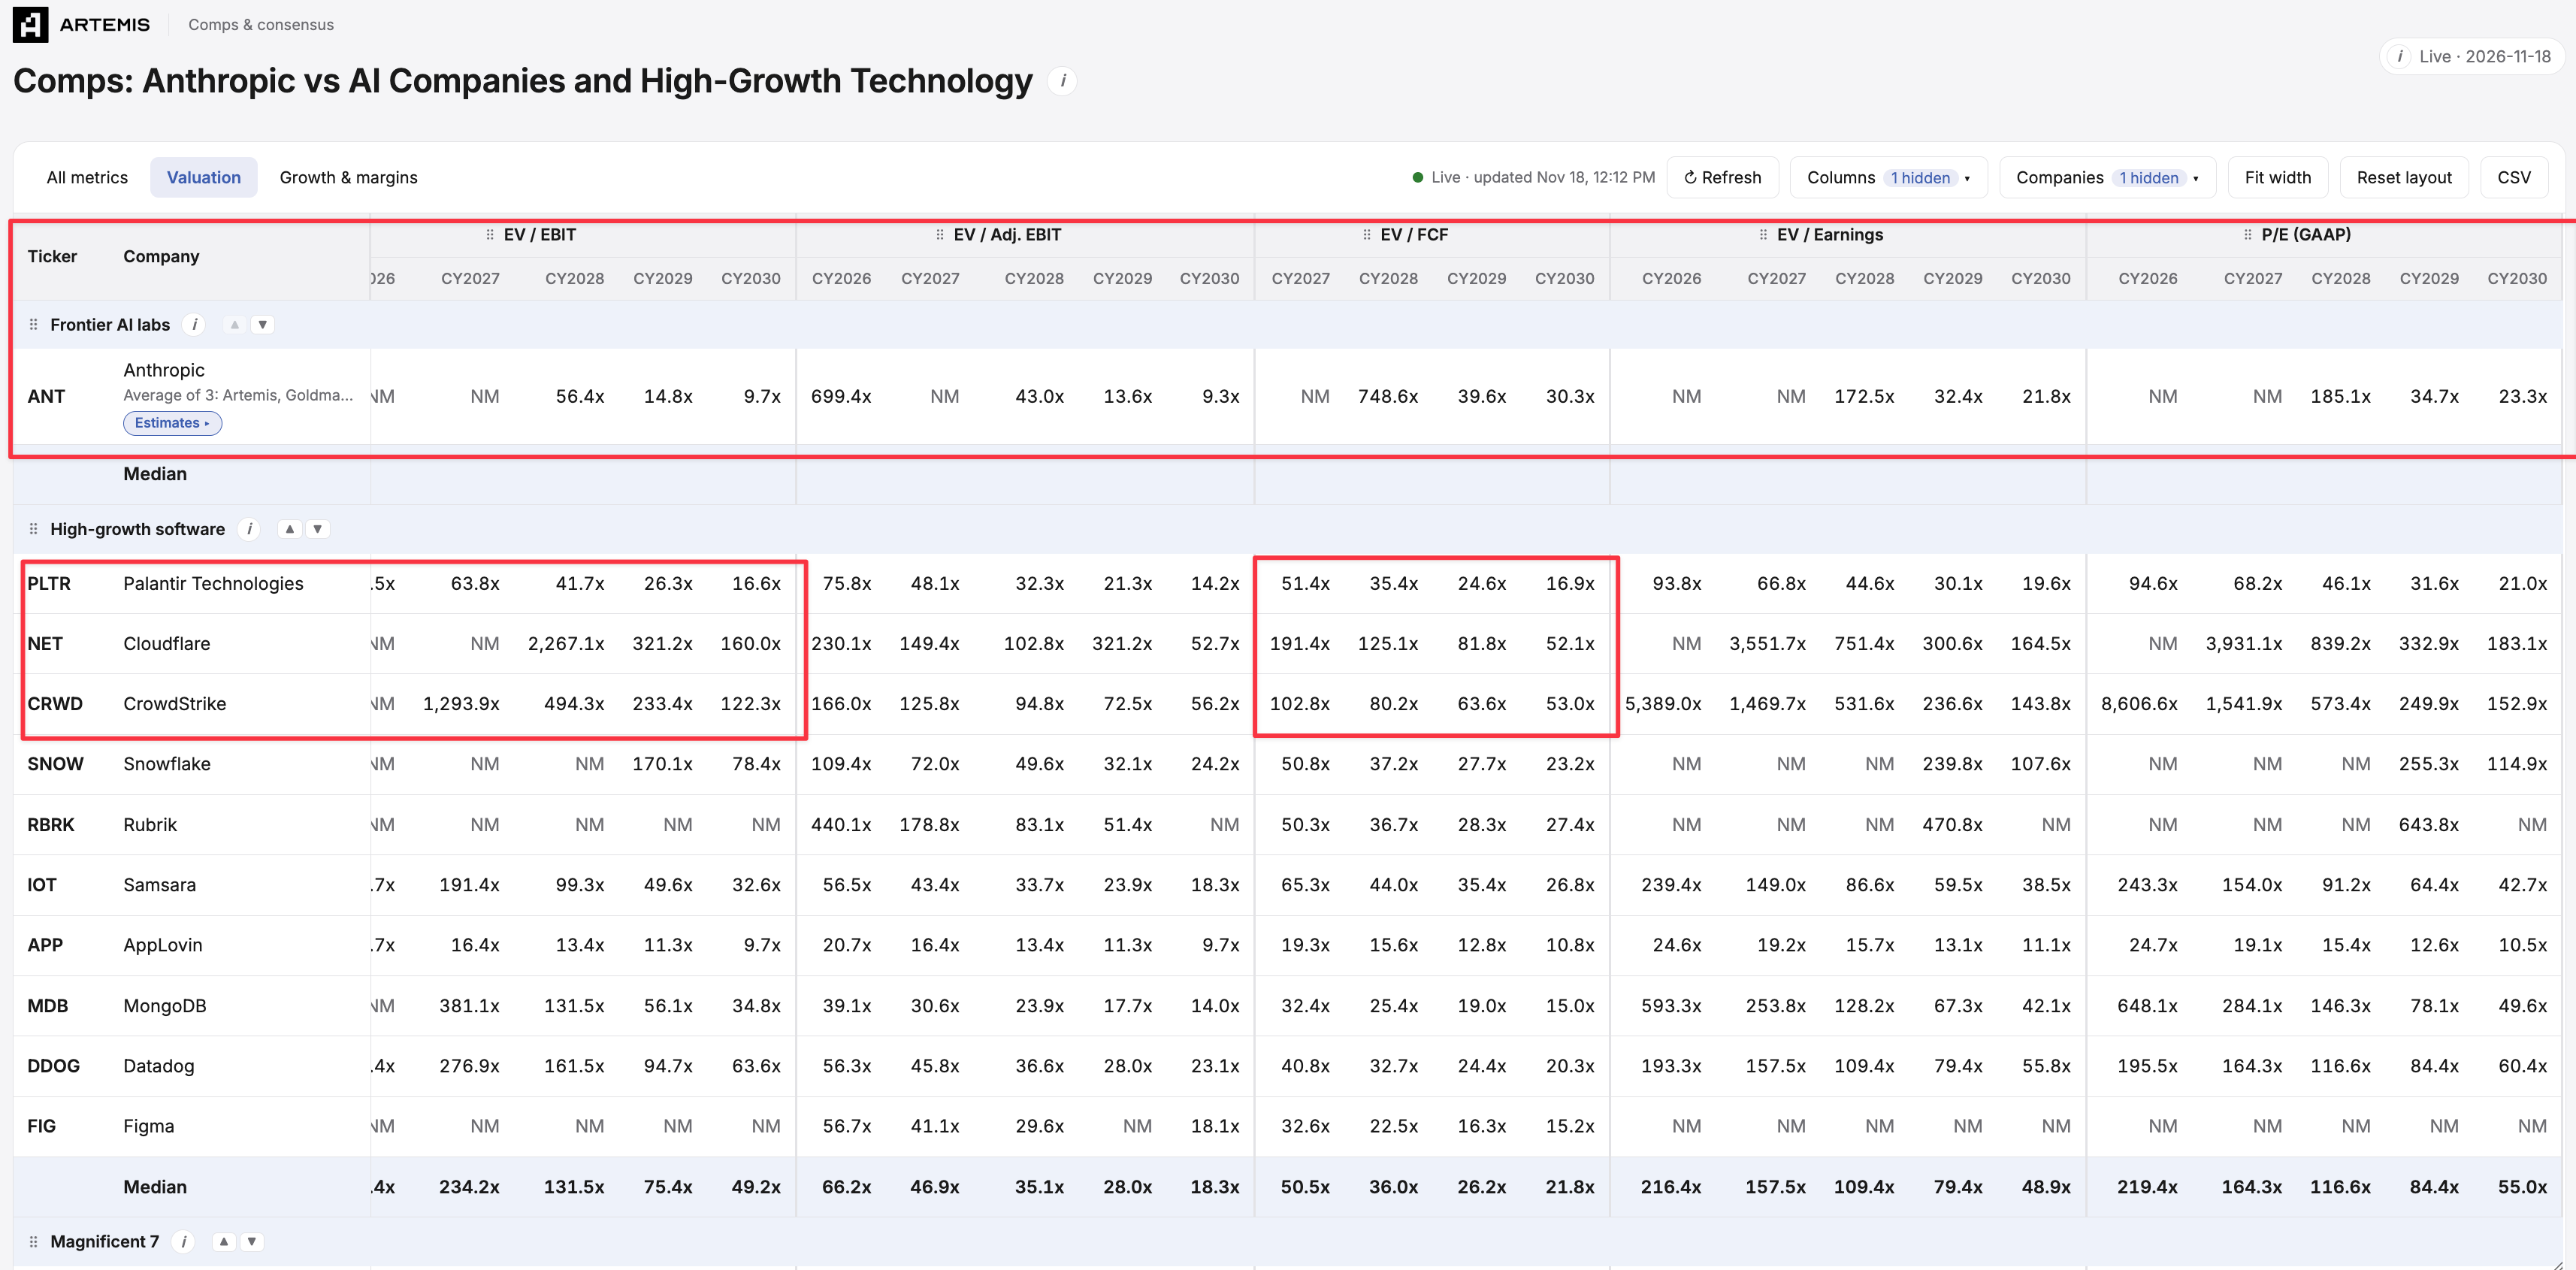
Free Cash Flow and Earnings are more difficult to forecast but even then Anthropic doesn’t look crazy at less than 10x 2030 EBIT (assume a 20-30x EBIT could stand to double or triple)
Anthropic Model
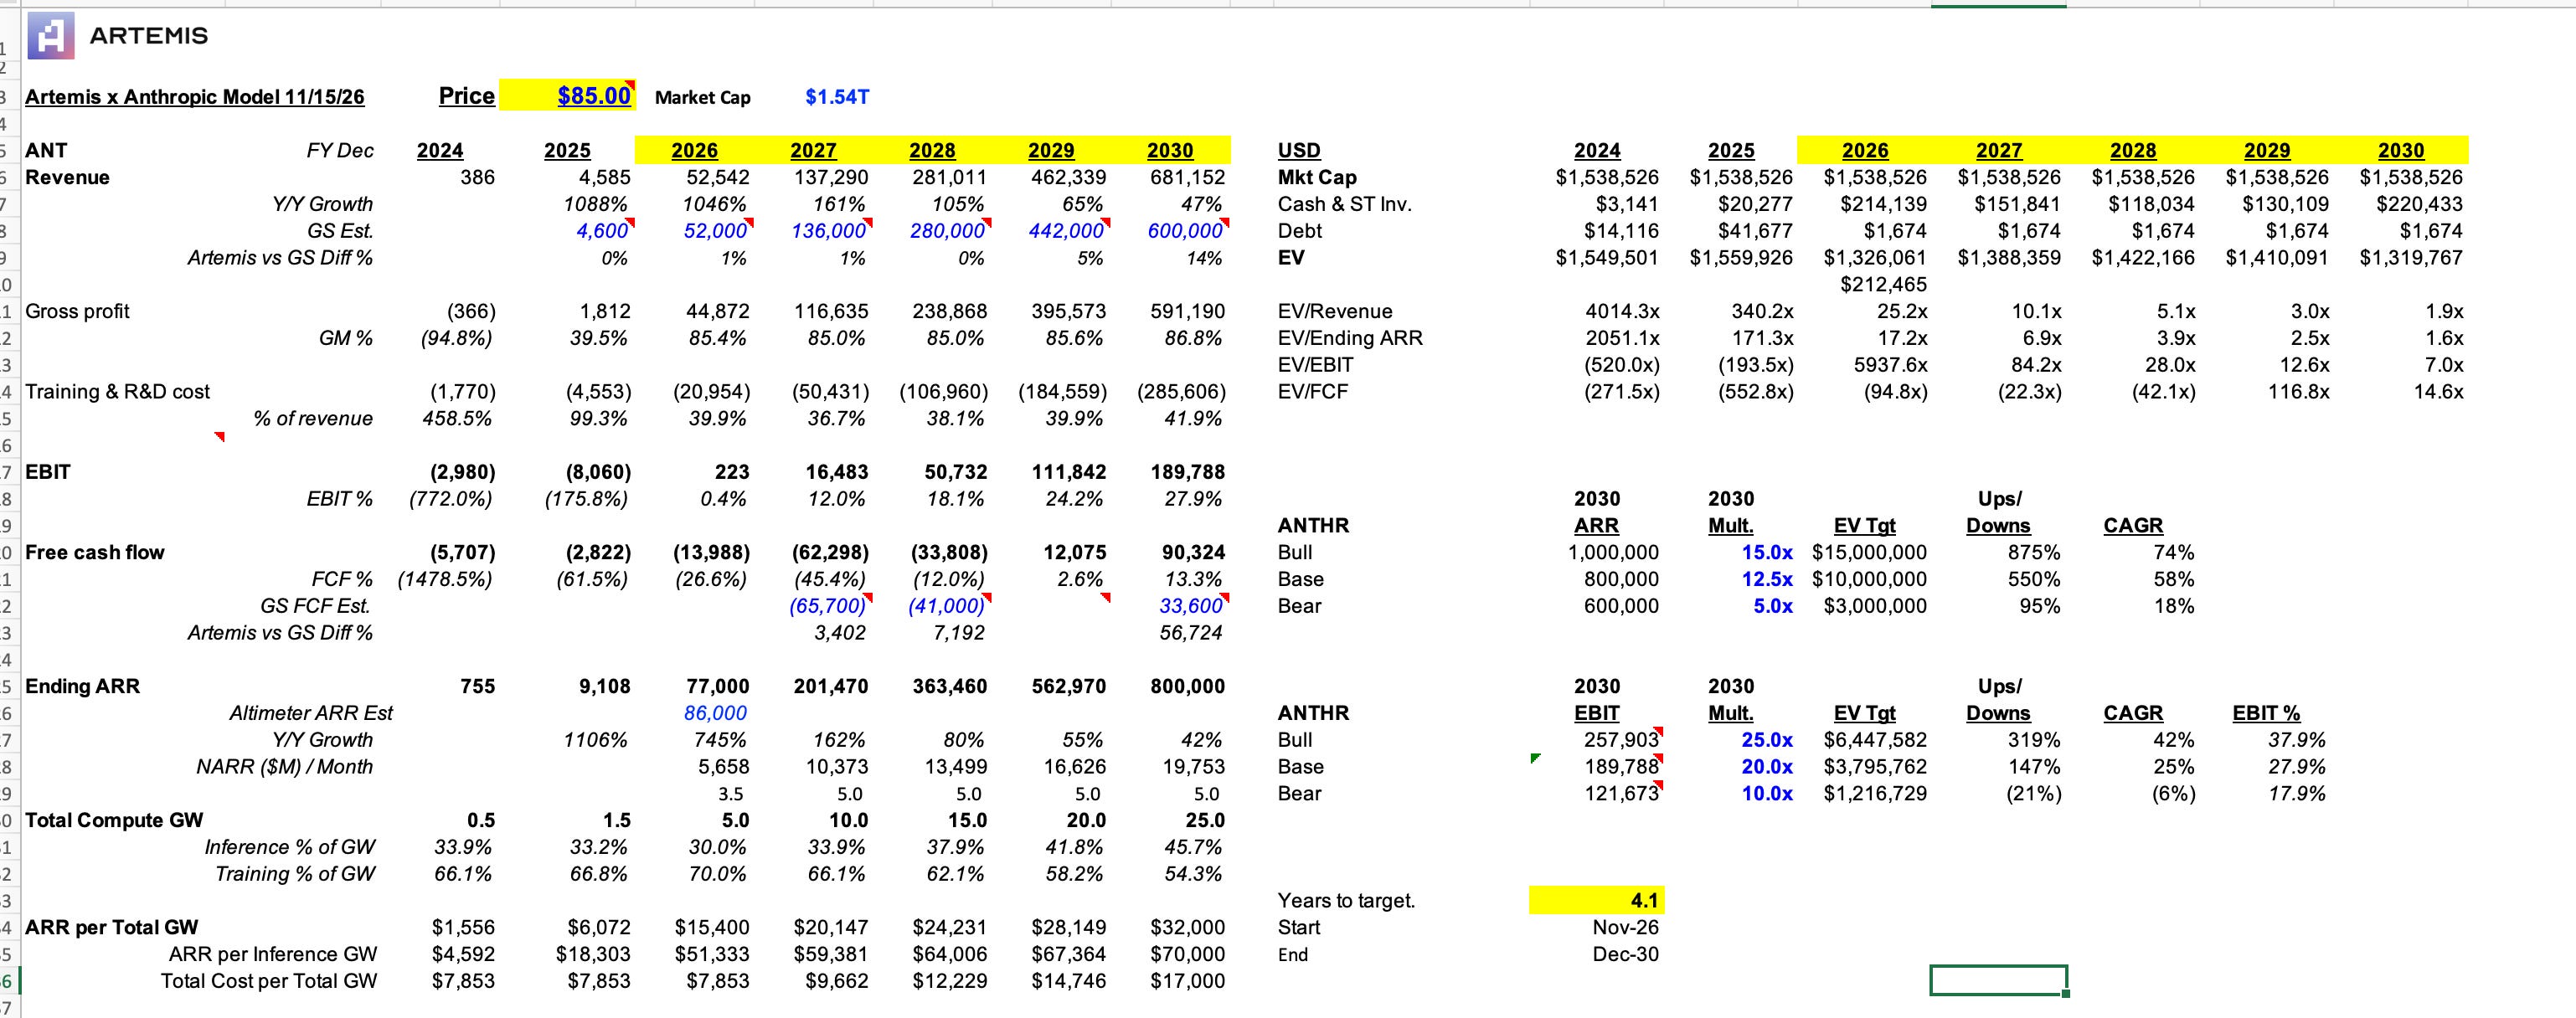
Here’s my financial model for where I see Anthropic over the next 4 years. And to be honest we might still be underestimating the growth curve. Note our assumptions aren’t crazy relative to Goldman’s estimates for revenue and free cash flow.
Here are the core assumptions:
1. Revenue:
ARR in 2030:$1.8T of Enterprise spend in 2030 up 10x from 2026 Estimate of ‘26 $180B ARR of AI Enterprise spend from Menlo Venture survey. Fortune 5000 go from 0.1% token spend of OPEX to 10% and agent adoption goes from <1% to 10%+. Note we don’t account for Ode with Anthropic (take rate on services), drug discovery / life sciences, other areas ... we just project out token spend to replace / augment knowledge work. Those business lines could easily add another $500B ARR to 2030.
Marketshare: ANT owns 50% of enterprise spend in AI in 2030 -- we think Anthropic and OpenAI are a duopoly
Cost:
Anthropic Compute Assumptions
$70B ARR per inference GW in 2030 (Altimeter has $86B ARR in Q4’26)
$17B Cost per GW driven by Anthropic Direct and owning / leasing data centers directly - less $ and faster time to launch
5 GW already secured by EOY 2026 and 11 GW already locked, Anthropic will need another 14 GW to service the $800B ARR in 2030.
At $10-15B of GW for the 14 GW required with less CAPEX spend and cheaper $ per GW, that’s another $150B - $200B required to service the $800B ARR in 2030. With a $200B+ balance post IPO, Anthropic will be able to fund the additional build out.
AI Fear = Good for Anthropic
There’s a lot of fear in the last few weeks around:
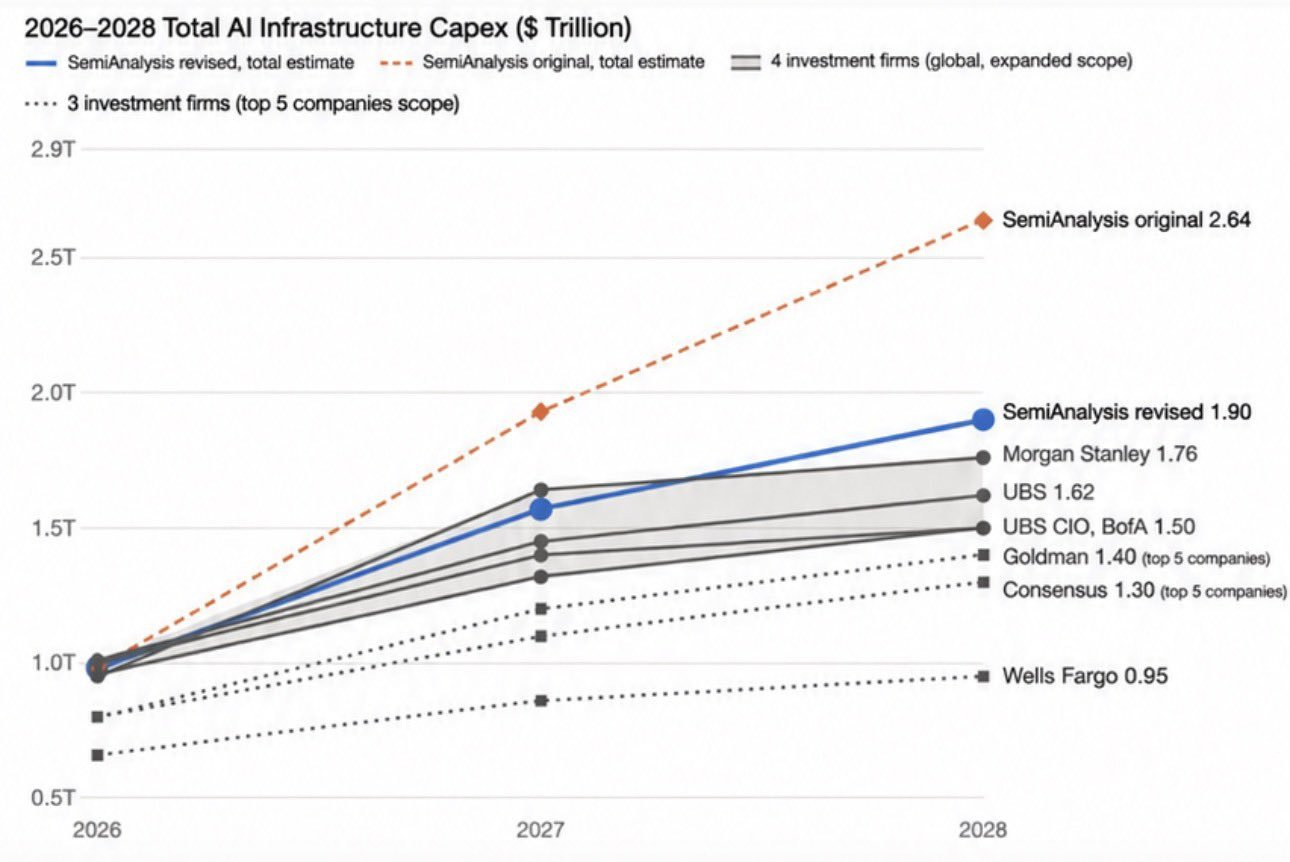
AI data center built out since the Democrats took the house / senate and the governor of Texas flipped blue and fears that data center build out will be pushed by 6 months from H2’2027 to H1’2028 based on the Semi Analysis revision:
Jensen resigning from NVIDIA also prompted fear among AI investors about how much spend will go towards AI startups, neolabs and neoclouds that often times are the core consumers of frontier models.
Both events are extremely good for Anthropic
Open source bear case for Anthropic weakened by Jensen/Nvidia situation
Open source loses access to NVIDIA chips and now need to train exclusively on Huawei or other chips in order to distill and train.
AI Capex Spend will concentrate from Anthropic and OpenAI leading to cheaper and better deals as frontier / open source labs and neoclouds have less funding from NVIDIA.
Anthropic will have a duopoly over the next 5 years barring any government regulation and what happened with Jensen is ultimately beneficial for Anthropic.
Bear Case
While Anthropic has had a meteoric rise, their fall in revenue could also be quite quick.
Here are the various bear cases:
Tokens commoditize: open source is able to run well on Huawei and circumvent export controls and Anthropic loses pricing power
Founder risk: the founding team seems highly mission oriented and there’s a chance as a public benefi corporation, the mission may override shareholder interests
Talent drain post-IPO: researchers become very wealthy and aren’t incentivized to improve frontier models.
Jensen returns to Nvidia: removes a key tailwind for Anthropic having less open source competition.
IPO timing risk: Anthropic may be going public at its peak with revenue to roll over in December and Anthropic will be free cash flow negative for at least 3 more years.
Government nationalize the AI labs: if Anthropics revenue is in the trillions and actual employment is impacted and mass employment is replaced by agents, there may be a national tax on labs or the government decides to nationalize them.
Lack of focus: how does one run a company is trying to build intelligence for companies to run autonomous engineers AND find the cure to cancer. There’s a lot of product surface area currently at Anthropic.
Conclusion
3 weeks ago, I thought Nvidia was going to be the world’s first $10T company.
However, Meta’s Muse just crossed 10M DAU. And you and I have been talking about how you’re using Muse more and more!
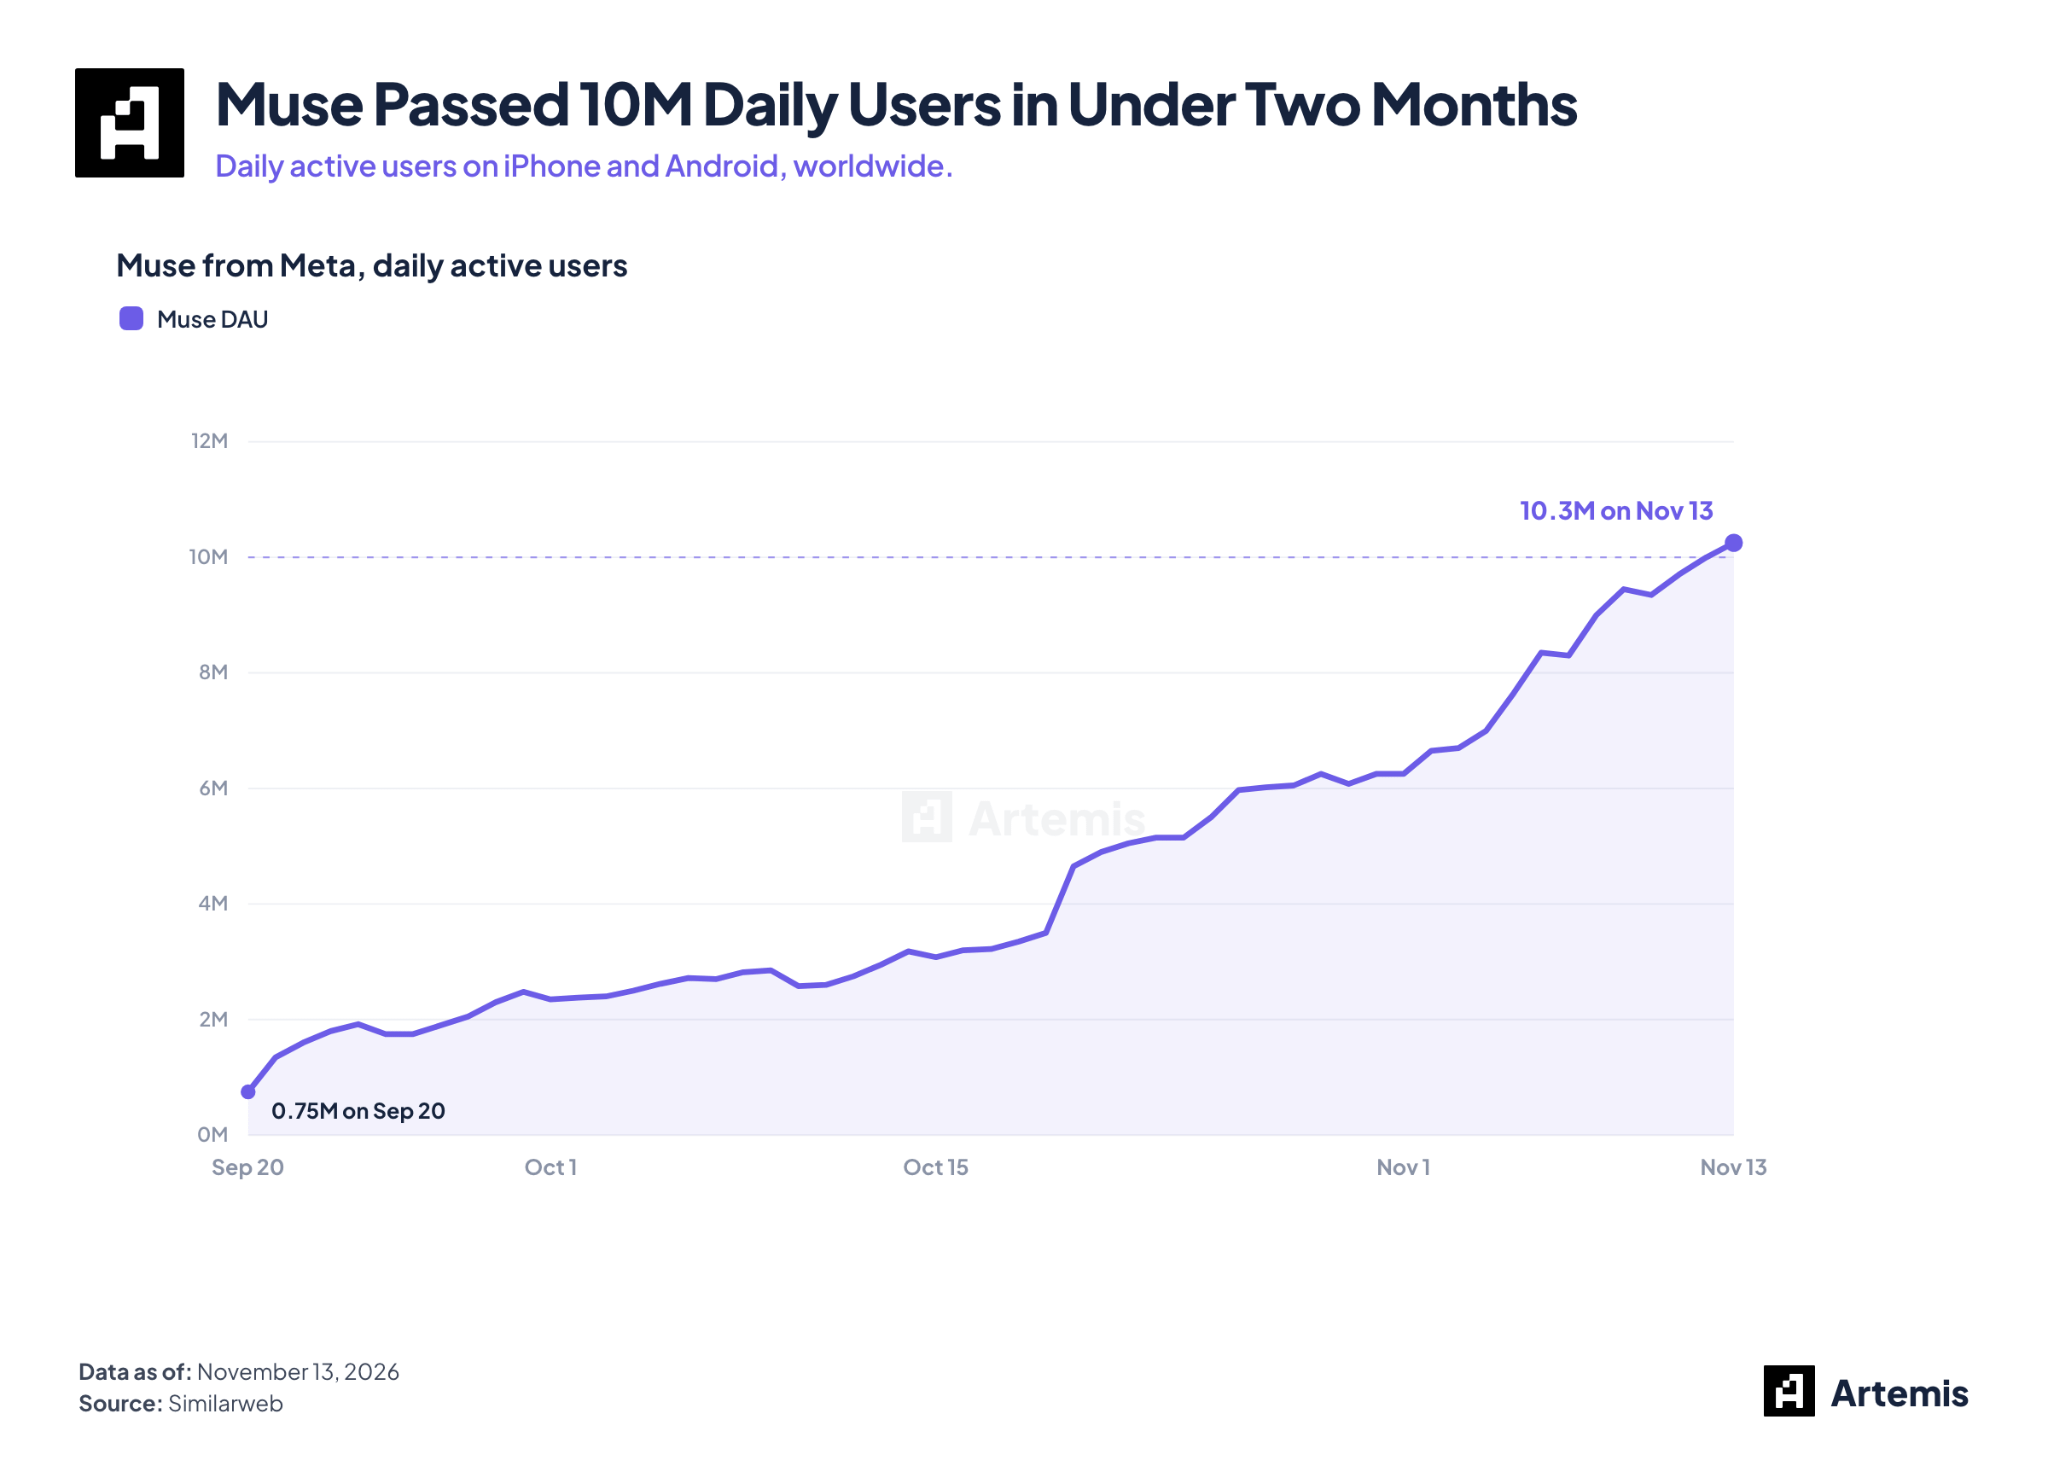
The market is clearly shifting their consensus bet from AI infrastructure / bottleneck (neoclouds , GPUs, CPUs, memory) in early / mid 2026 towards AI applications like Meta (Muse), SpaceX (Grokbot).
Anthropic BOTH designs chips and builds data centers AND the most valuable part of the stack which are the frontier models and tokens that businesses lik Artemis are willing to pay 100x more for AND the applications like Claude Code, Claude Cowork, Duet (the Muse competitor) that consumers and busiensses use.
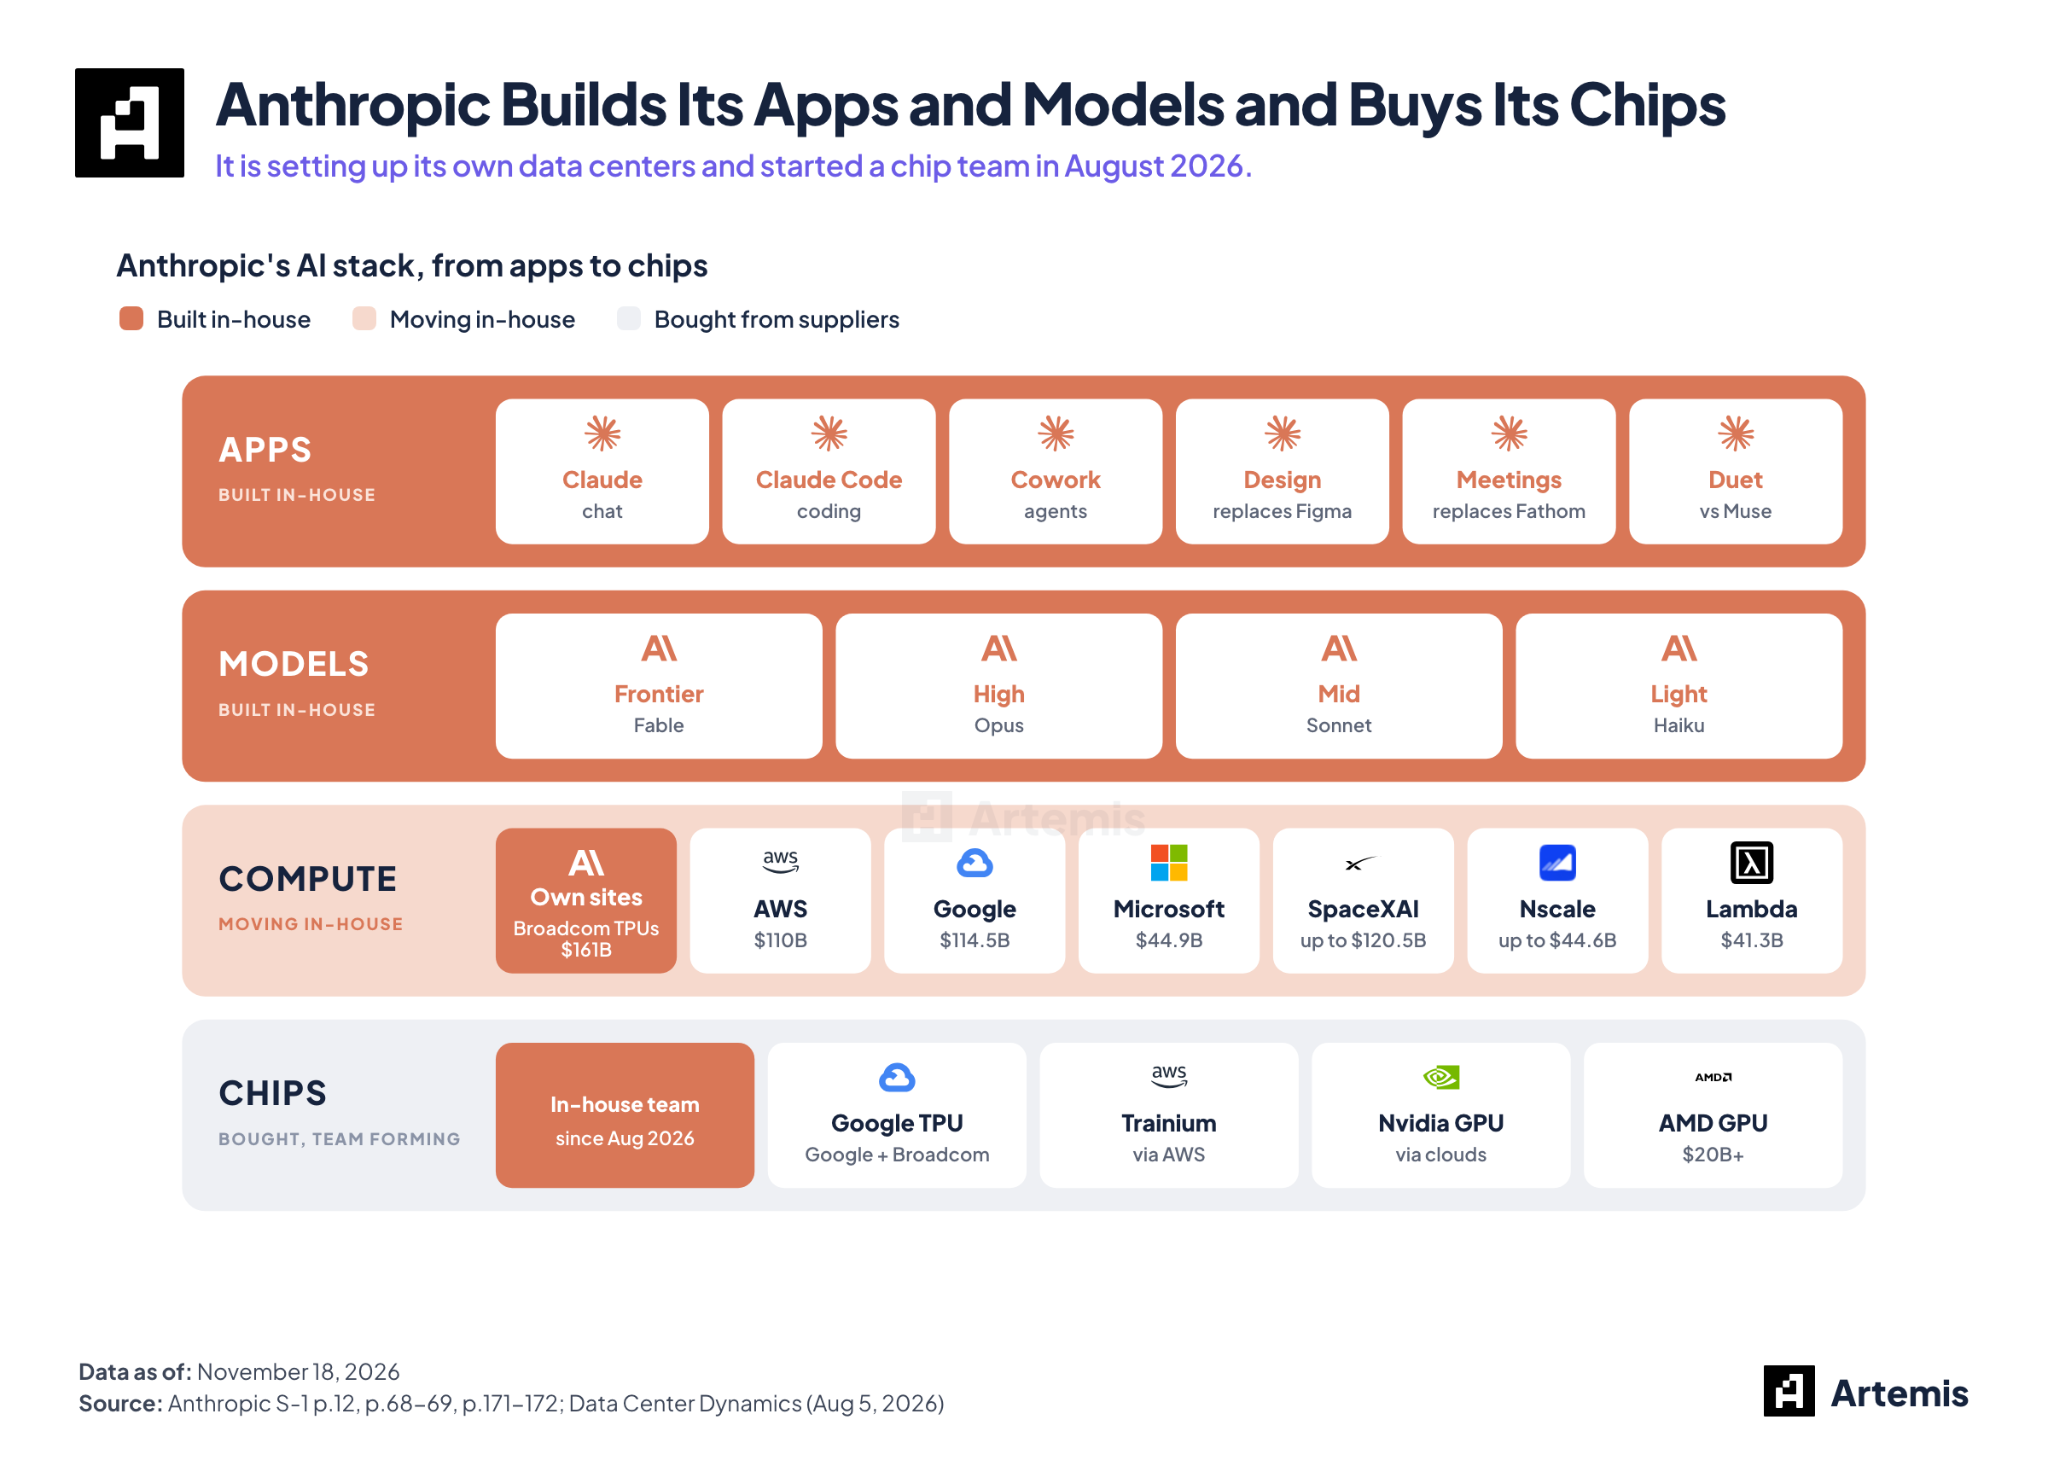
The market will start rushing towards AI applications and majority of them will be powered by Anthropic.
I believe the first $10T company won’t be a company in the AI data infrastructure stack but in AI applications that consumers or businesses use globally.
We think that’s Anthropic.
Love,
Jon
This post and the accompanying model are the personal opinion of Jon Ma, published for informational and educational purposes only. Nothing here is investment, financial, legal, or tax advice, and nothing here is a recommendation or solicitation to buy, sell, or hold any security, including shares of Anthropic.
Conflicts of interest. I hold economic interests in Anthropic through SPVs, and Artemis Analytics holds economic interests in Anthropic directly and/or through pooled investment vehicles. We stand to benefit if Anthropic’s valuation rises, and we may buy or sell these interests at any time without updating this post. Artemis is also a customer of Anthropic: our products are built in part on Anthropic’s models. Assume I am not a neutral observer.
Not an adviser. Neither I nor Artemis Analytics is a registered investment adviser or broker-dealer. I do not know your financial situation, objectives, or risk tolerance.
The model. The spreadsheet is an illustrative tool, not a forecast you should rely on. It contains estimates, projections, and scenarios (including ARR, revenue, margins, free cash flow, compute capacity, market share, and 2030 valuation) that are my own or derived from third-party sources, including Anthropic’s S-1 filings, press reports, and published research from SemiAnalysis, Menlo Ventures, and others. Small changes in assumptions produce very large changes in output. It may contain errors, and I may revise it without notice. Figures other than those taken directly from Anthropic’s SEC filings are not reported results and have not been verified with or endorsed by Anthropic.
Forward-looking statements. Statements about Anthropic’s IPO, its pricing, where the stock may trade, and its future financial performance are speculation. Bull, base, and bear cases are illustrative scenarios, not predictions or guarantees. Actual results may differ materially.
The offering. This post is not an offer to sell or a solicitation of an offer to buy any security, and it is not part of any offering by Anthropic or its underwriters. Read Anthropic’s prospectus filed with the SEC before making any investment decision.
General. Third-party information is believed to be reliable but has not been independently verified, and I make no representation as to its accuracy or completeness. All investing involves risk, including the loss of your entire investment; past performance does not indicate future results. Do your own research and consult a licensed professional. Anthropic is not affiliated with Artemis Analytics and has not reviewed or approved this content.