

Record IPOs, everyone selling everything everywhere all at once. Welcome to This Week in Markets!
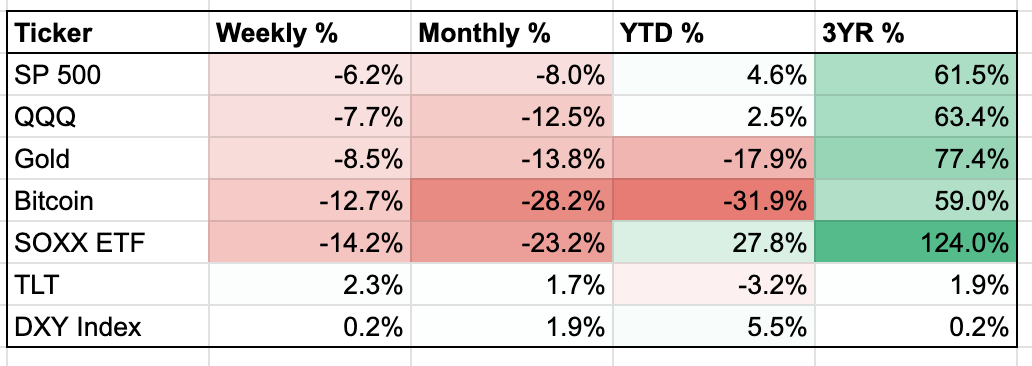
Weekly Performance - OUCH!
The bizarre part: earnings were good! Many companies beat analyst estimates and some even raised their forecast for the next year. Here’s a quick breakout and as you can see, a lot of green in a sea of red.
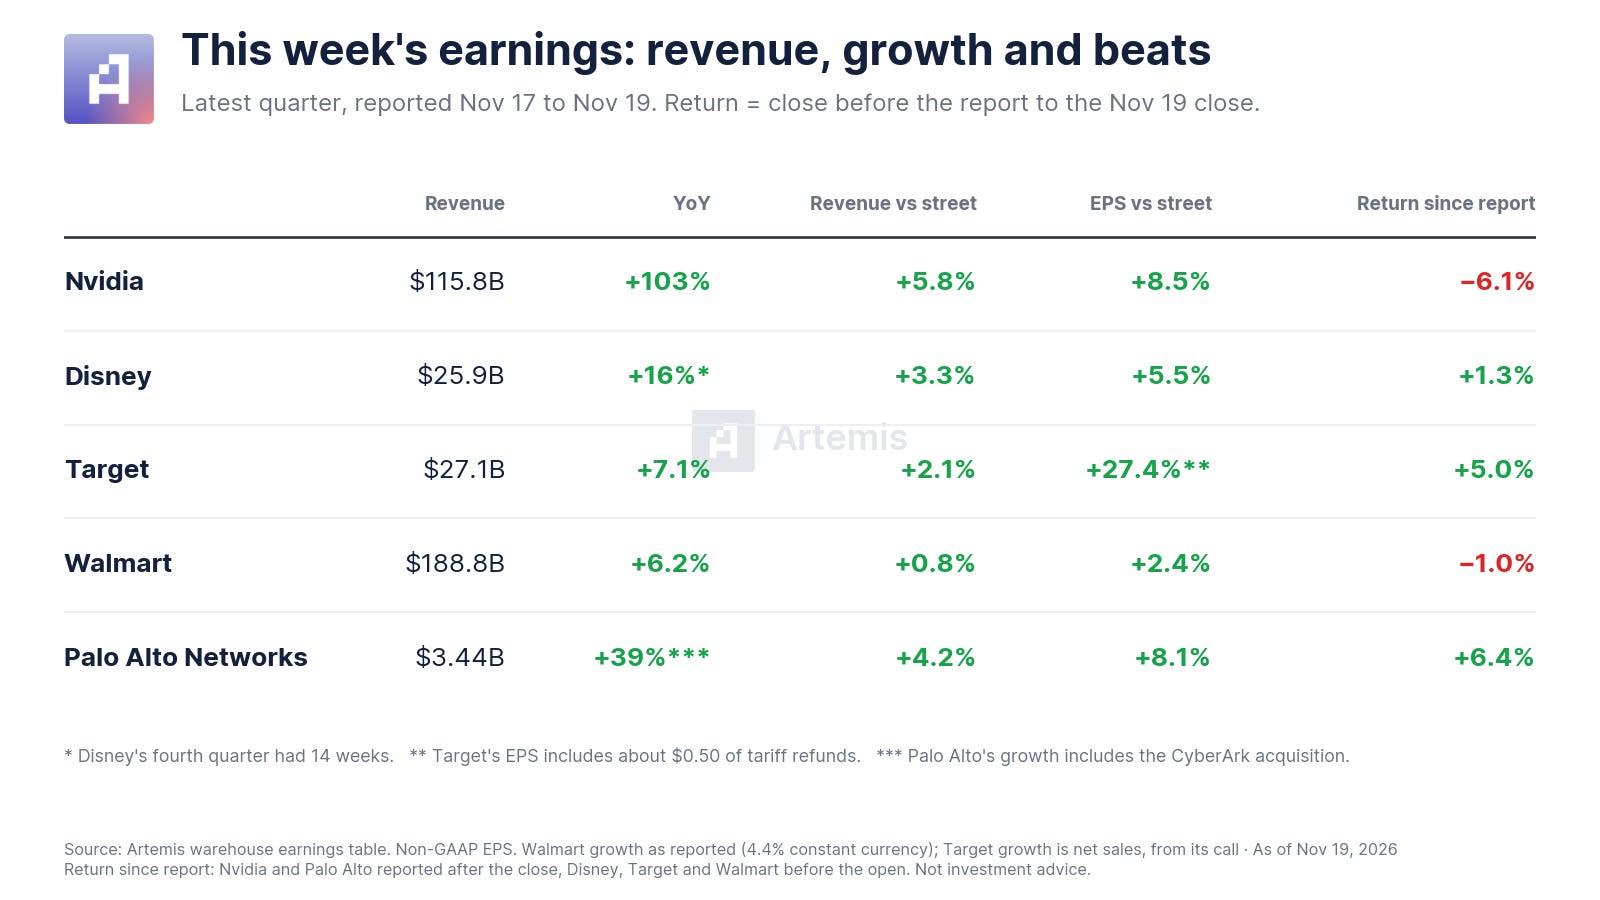
Possibly the most anticipated earnings event of all time, Nvidia, did not disappoint. Revenue was a record $115.8B, up 126% year over year and Nvidia even raised fiscal 2028 growth to about 75% from 70%. Demand for Nvidia’s latest chip, Vera Rubin, was astonishing with revenue of nearly $20B, the fastest ramp in Nvidia’s history. You would think this would all be welcome news - nope, the stock fell 2.9% the next day.
If Nvidia can’t save the market, then who can?
Anthropic IPOs
This past week our CEO Jon wrote a piece on how he thinks Anthropic could be the first $10T company. Anthropic is like no other business we have ever seen. The time to IPO, revenue growth and market potential are simply astonishing. His thesis is quite elegant:
If Fortune 500 companies spend 5-10% of OPEX on tokens with Anthropic / OpenAI that’s nearly $1-2T of AI spend a year from JUST Fortune 500.
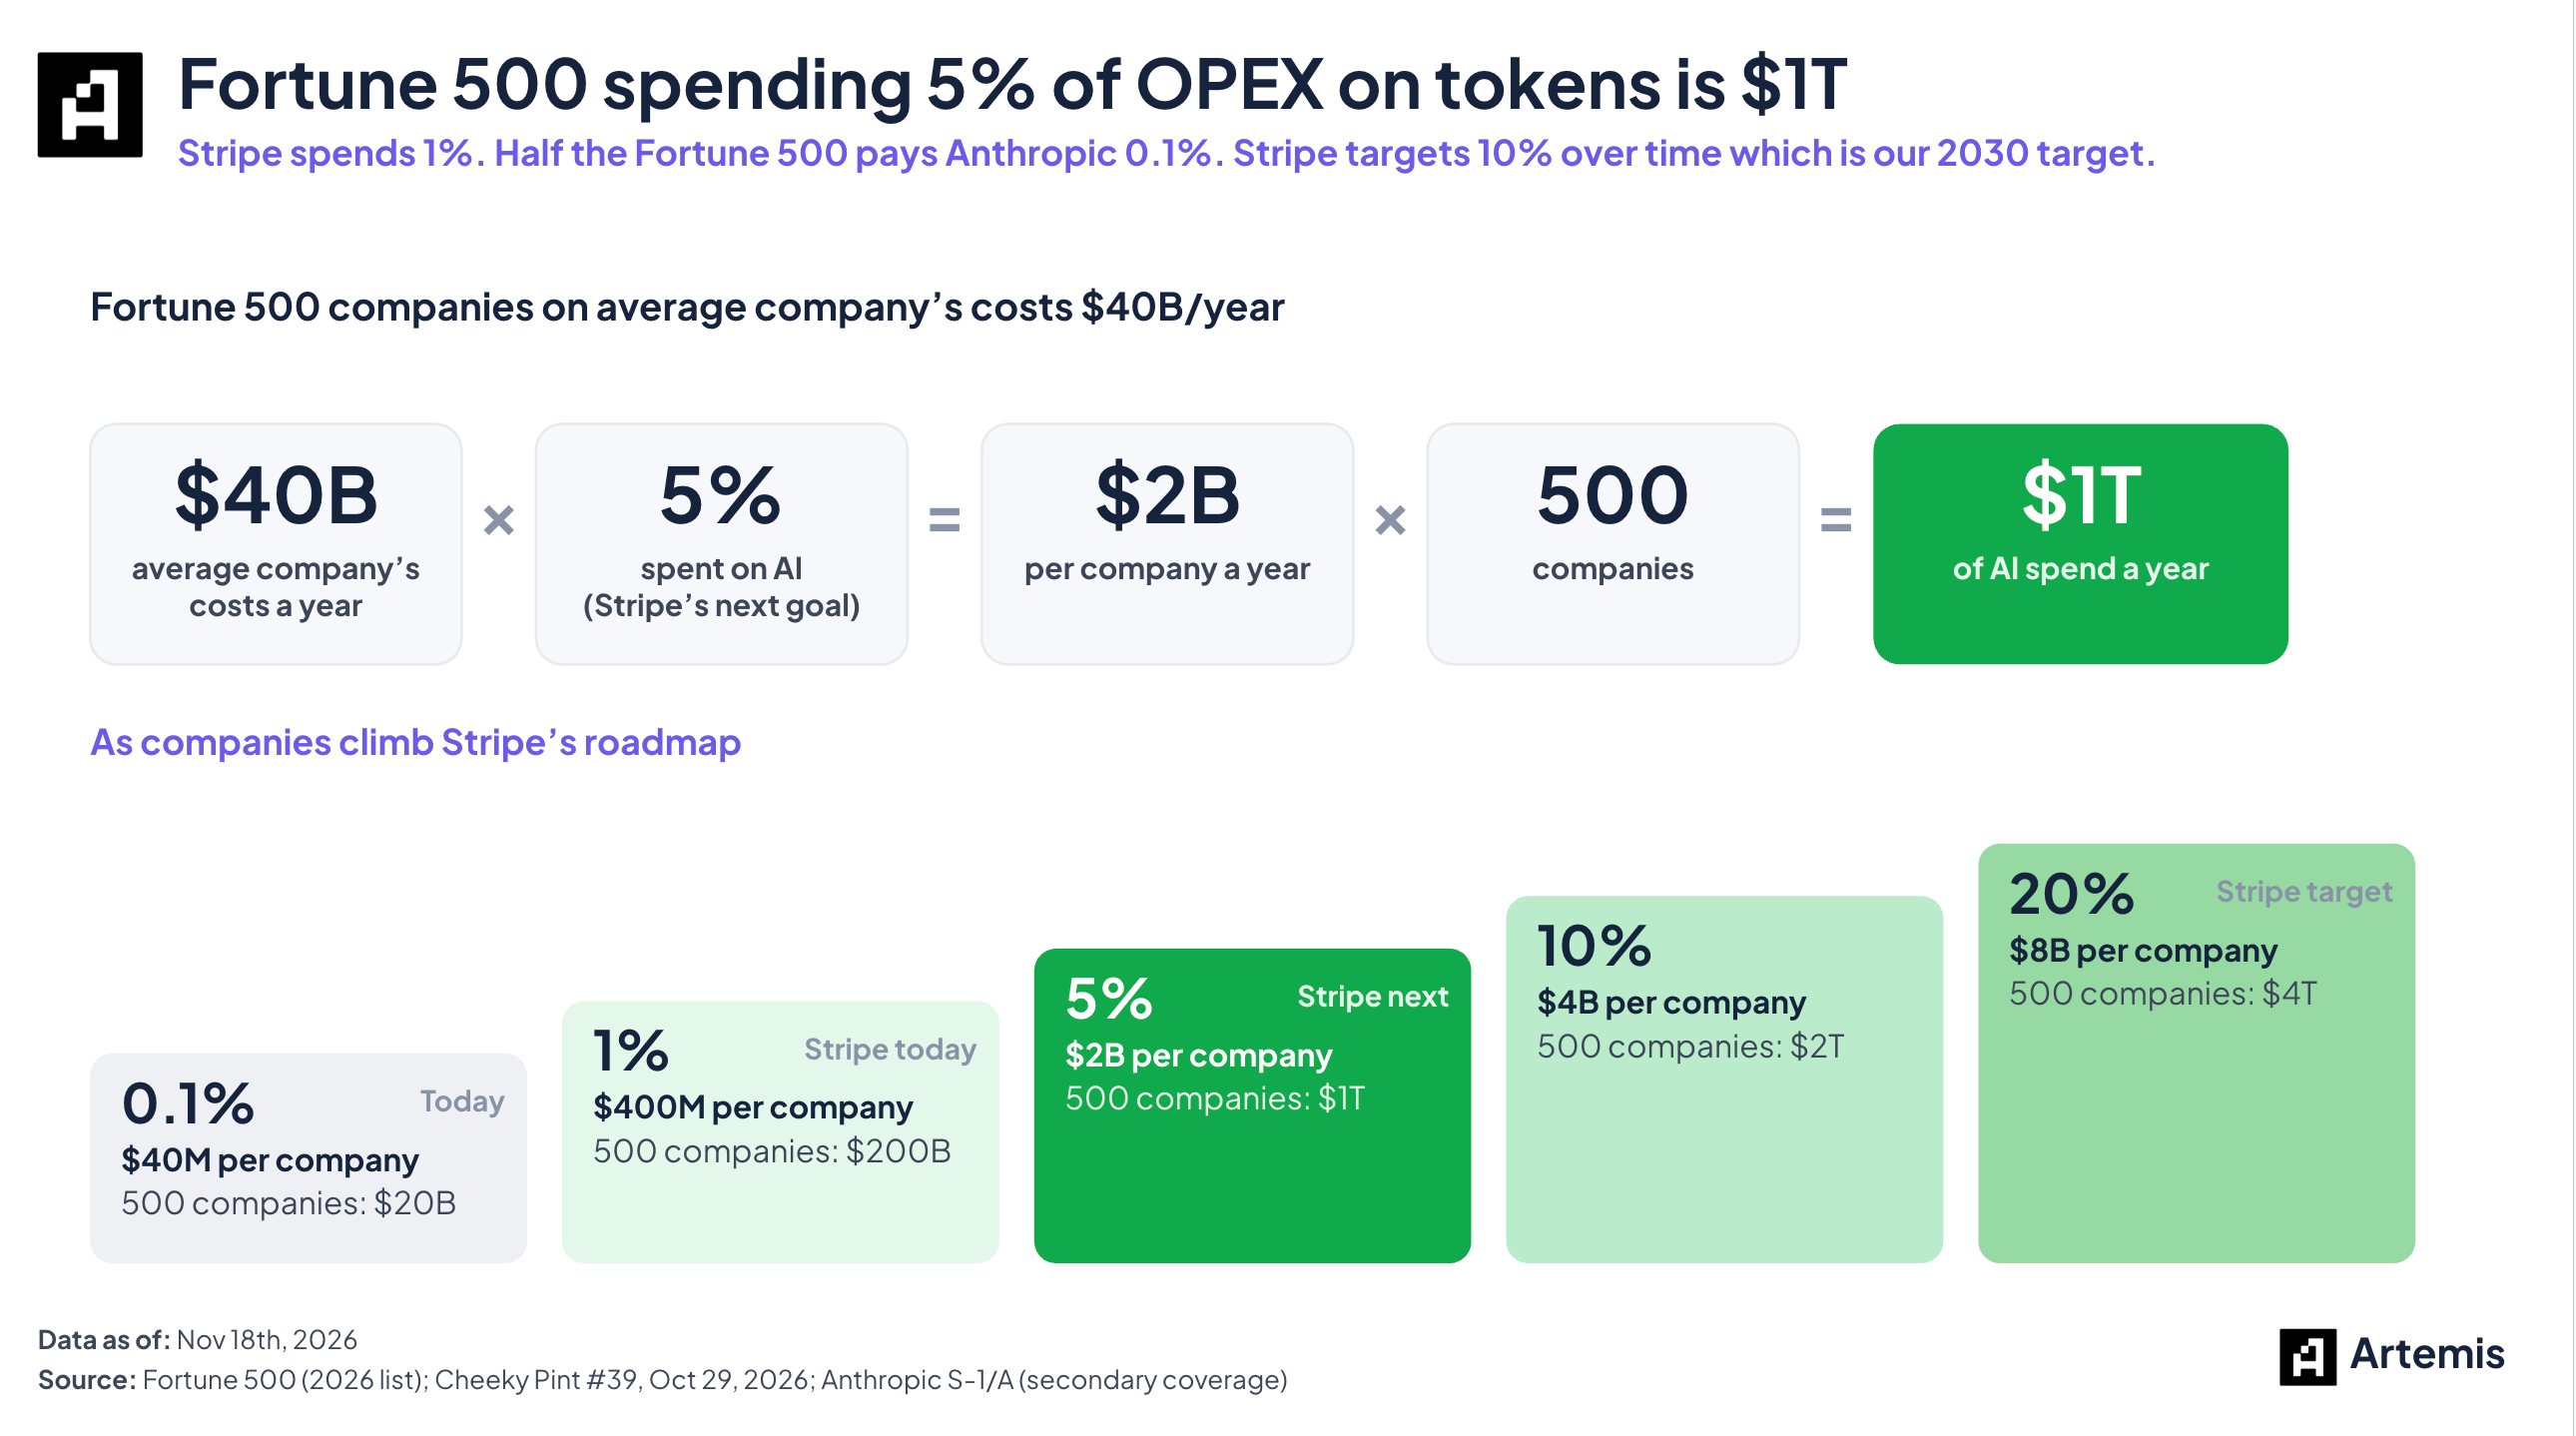
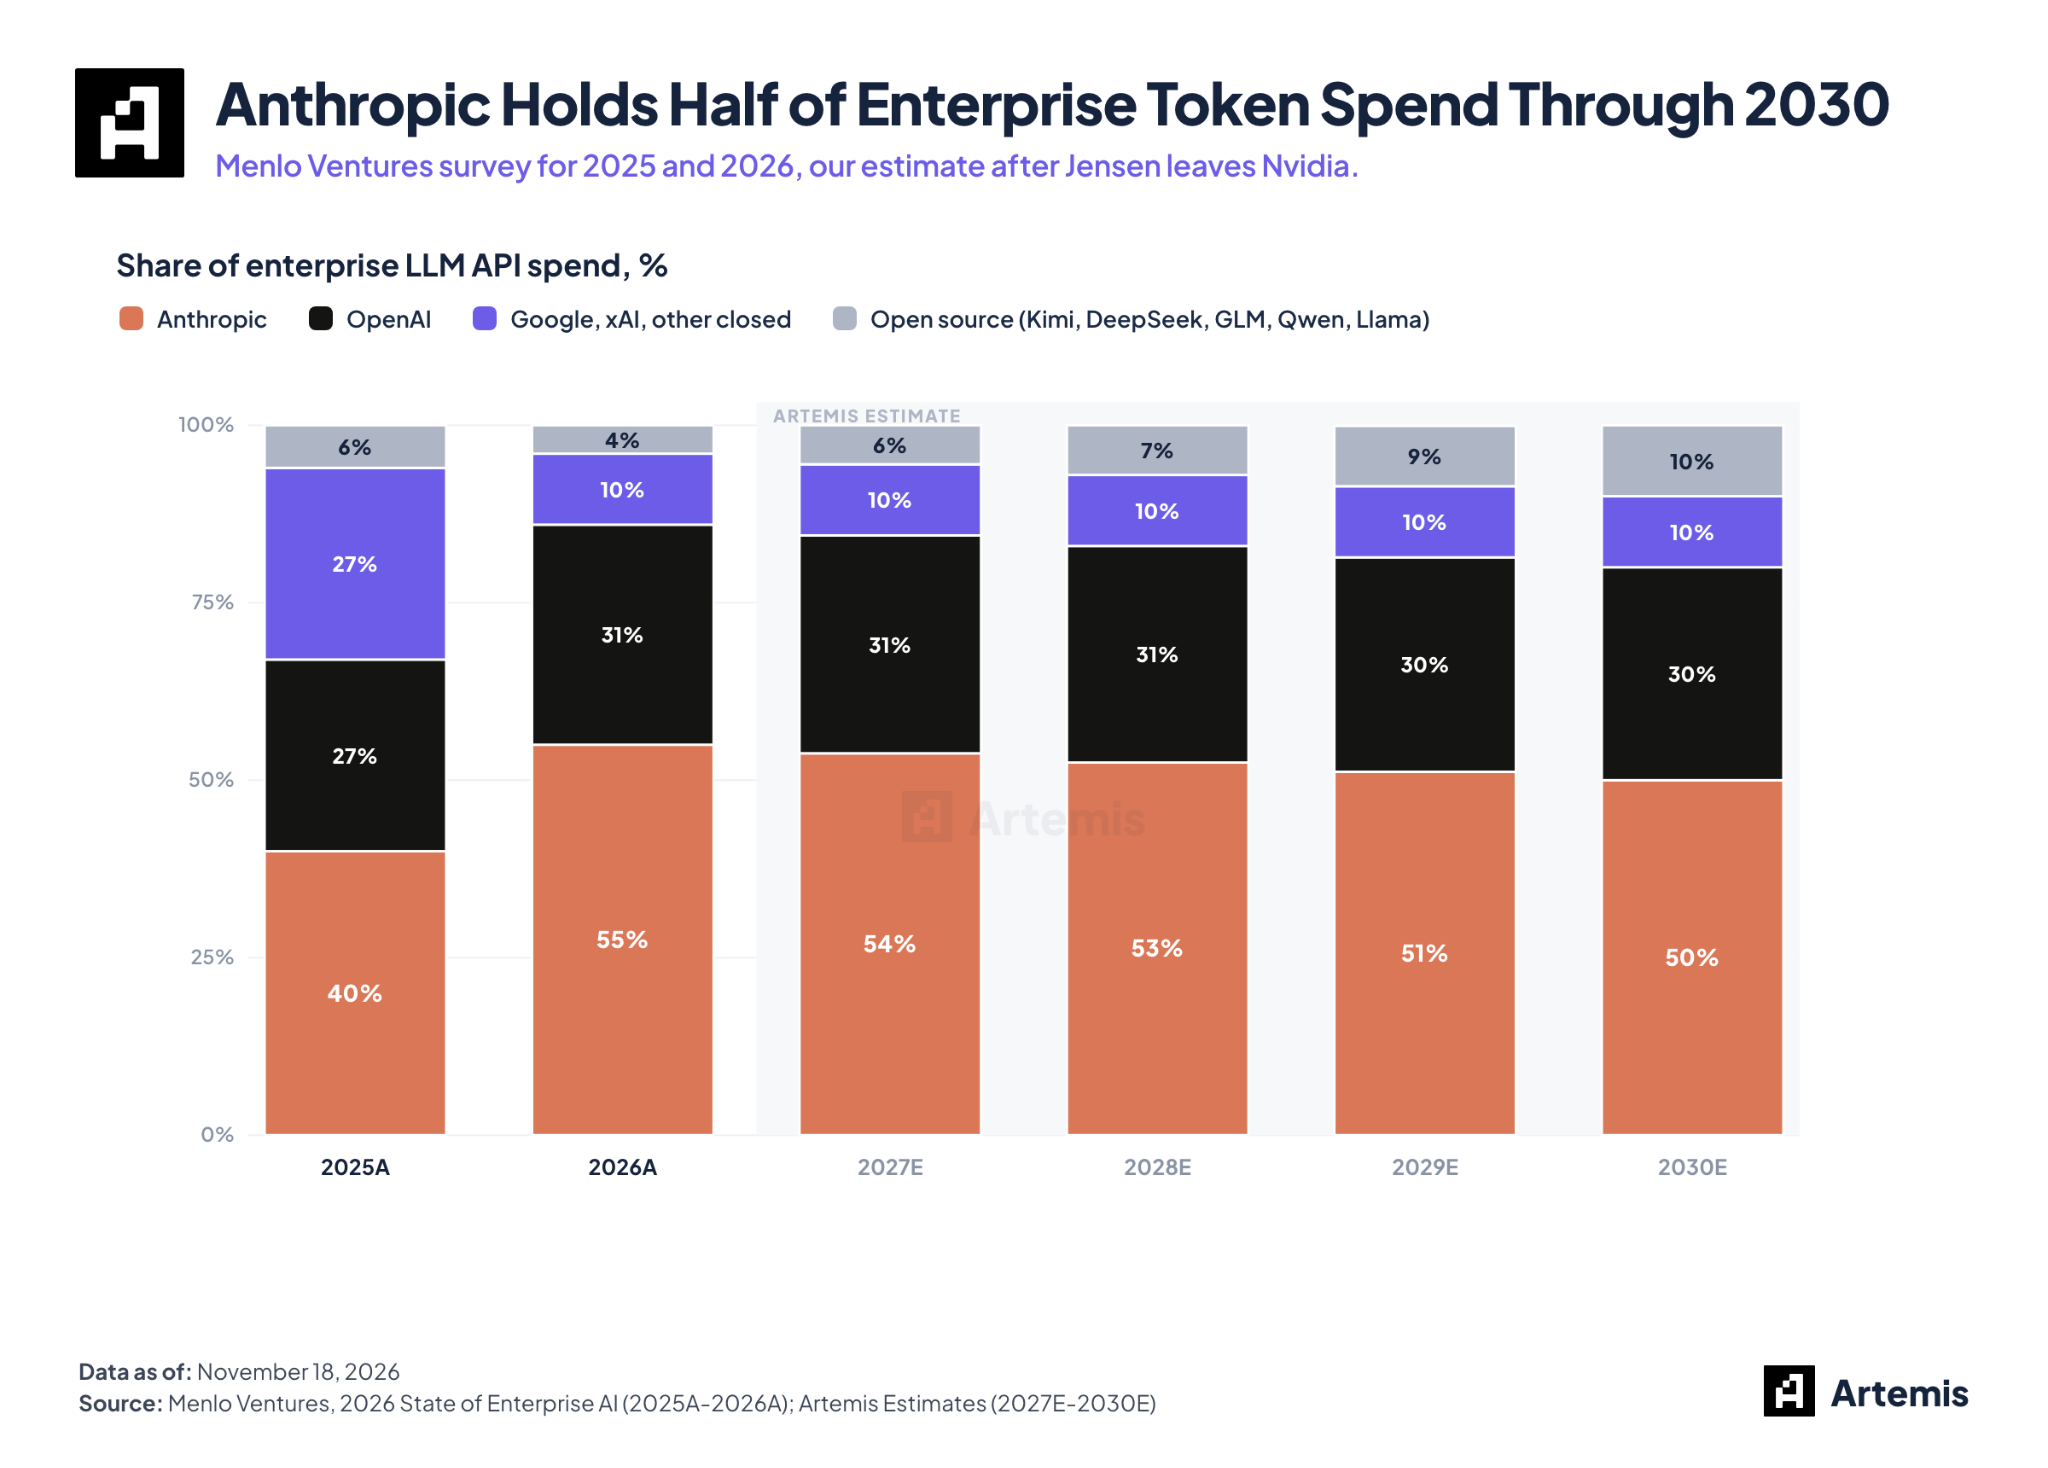
“In short, Anthropic will be the main provider of intelligence to the enterprise with >50% marketshare in 2030 of AI business spend. We think conservatively there’s at least $2T ARR spend in 2030 and that doesn’t even account for drug discovery if Anthropic figures out the cure for cancer and other new verticals we don’t even know about today or don’t show up in their financials just yet (e.g chip design).”
It’s a great piece, and I won’t do it justice by summarizing, so read for yourself here
Anthropic Exposure
With $80bn more money in its pocket, we asked which companies with the most riding on Anthropic. Here’s what we came up with:
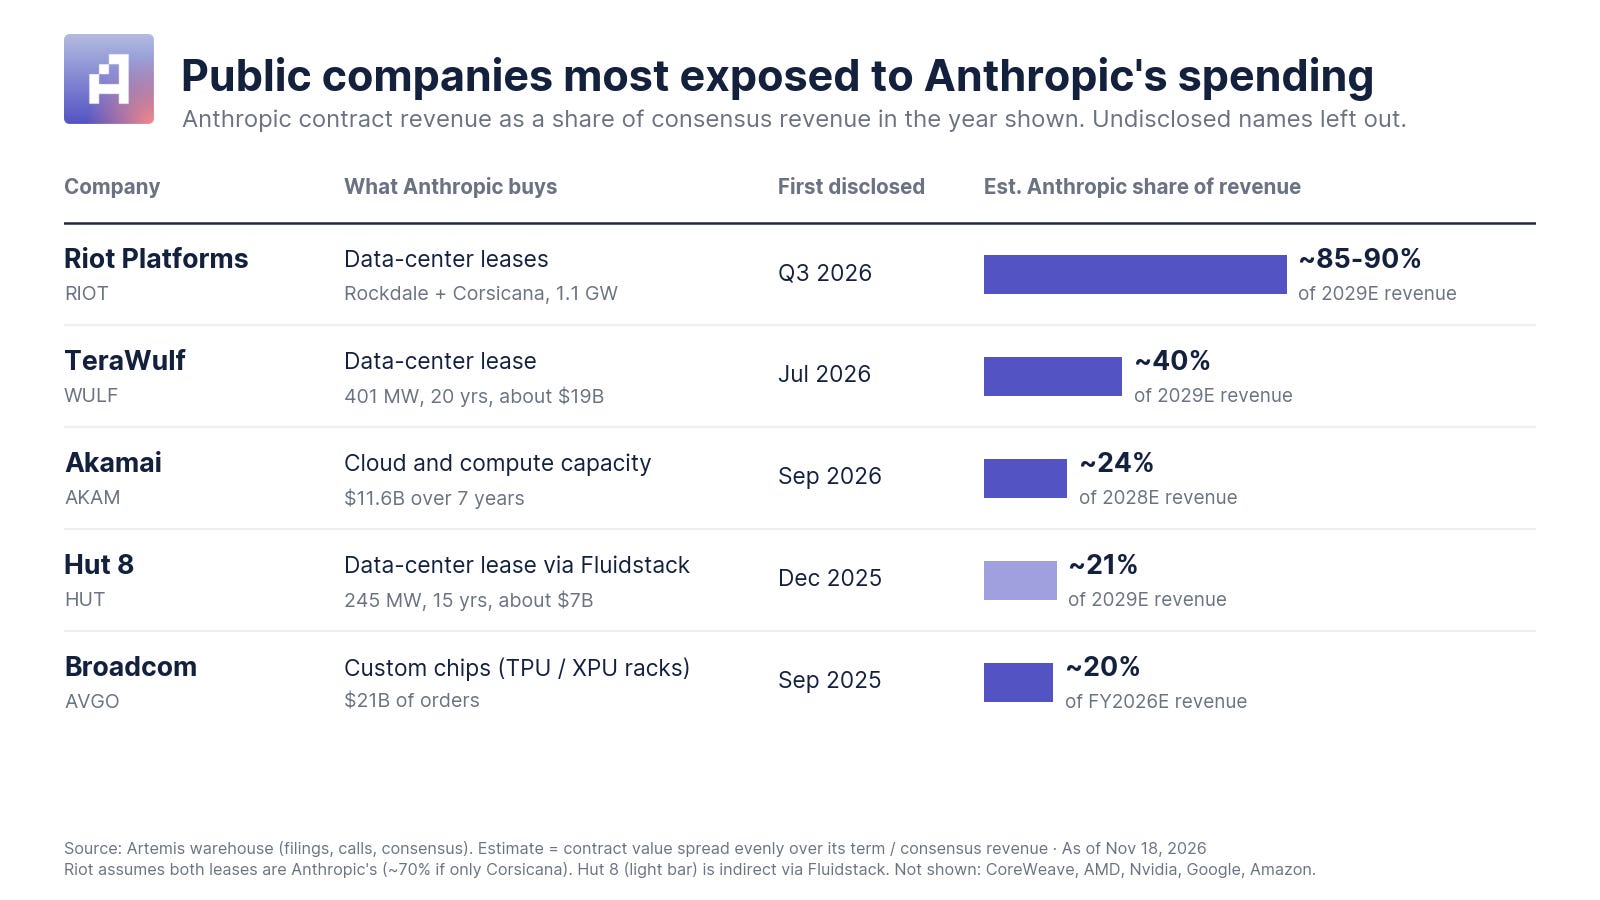
Most recently, Riot Platforms announced Anthropic has leased its 900MW Corsicana site, adding to Anthropic’s earlier commitment at Rockdale. Anthropic has two smaller commitments with TeraWulf and Hut 8, through a partnership with Fluidstack.
From Content Delivery to Compute Cloud: Akamai
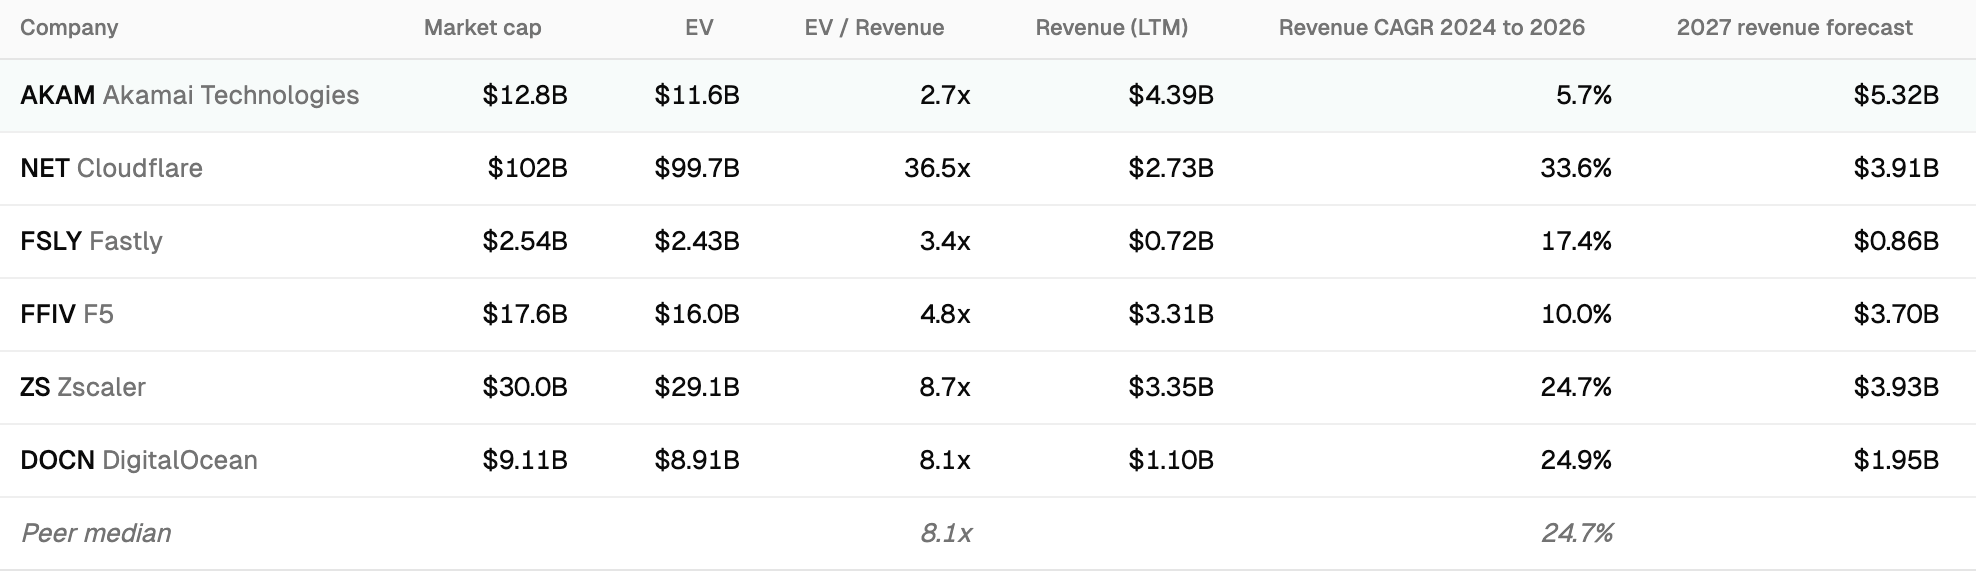
Akamai is a company that stood out to us. Akamai has a long history, starting out as a content delivery network, then expanded to web and application security, DDoS mitigation, identity management, and distributed cloud services. As a more mature company, Akamai trades at a discount to other security peers, but has a healthy free cash flow yield of 4.1%.
Akamai Comparables Table
The next growth driver
Akamai acquired an Infrastructure as a Service (Iaas) company, Linode back in 2022 (The funniest part was Akamai references the metaverse in the press release for buying Linode - of how far we’ve come) for about $900mn. While this story isn’t new, in September Akamai announced an $11.6bn deal with Anthropic for CPU compute, which sent Akamai’s backlog soaring to over $20B of demand. Akamai now expects revenue growth of 20% in 2027 and 30% in 2028, going from ~$4.5bn in 2026 to ~$7bn in 2028.
The intriguing part of Akamai is unlike some other neoclouds, Akamai has heathy free cash flow from their security business they can tap into for the infrastructure buildout. Over the last few years, they have used that free cash flow to repurchase stock and make investments. After raising $3.5B in zero-coupon convertible notes in May “to fund our growing CIS pipeline.” and pausing share buybacks, Akamai now has about $4.2B in cash as of Sep 2026.
On Aug 6, CFO Ed McGowan said Akamai is “temporarily pausing share repurchases” to put the capital into its cloud-infrastructure pipeline. He said “we haven’t seen a growth opportunity like this in a very, very long time.”
But Can They Execute?
Akamai already cut its FY2026 revenue guideance to $4.44-$4.465 billion from $4.445-$4.53 billion, on supply chain and third-party data center delays at two of the first three large deals. While the revenue is expected to be booked in the next quarter, analysts were skeptical. Here is James Fish, Piper Sandler analyst on the buildout:
But let’s face it, we’ve kind of missed compute or only been in line on virtually every quarter that you’ve had this business, and now you’re putting out a target that’s well above what we were all expecting. What’s giving the confidence, or why do you feel the need at this stage to put this out when, frankly, we haven’t seen you guys hit your compute numbers really yet
Ouch. Akamai has a lot to prove, especially as the data center buildout becomes more uncertain. But the opportunity could be historic. Here’s Ed McGowan, CFO of Akamai talking about their backlog
The demand signals we’re getting from our customers are insane. I’ve never seen a pipeline like what we have today, where we actually have to turn away business.
You’ve heard AWS say they’re sold out through 2028, and the reason for that is it’s the lack of power in the market. 2027 right now, if someone came to me and said, “I want to do an X billion dollars of deals and I want it in 2027,” we couldn’t provide that. No one can. There’s just not that sort of power availability
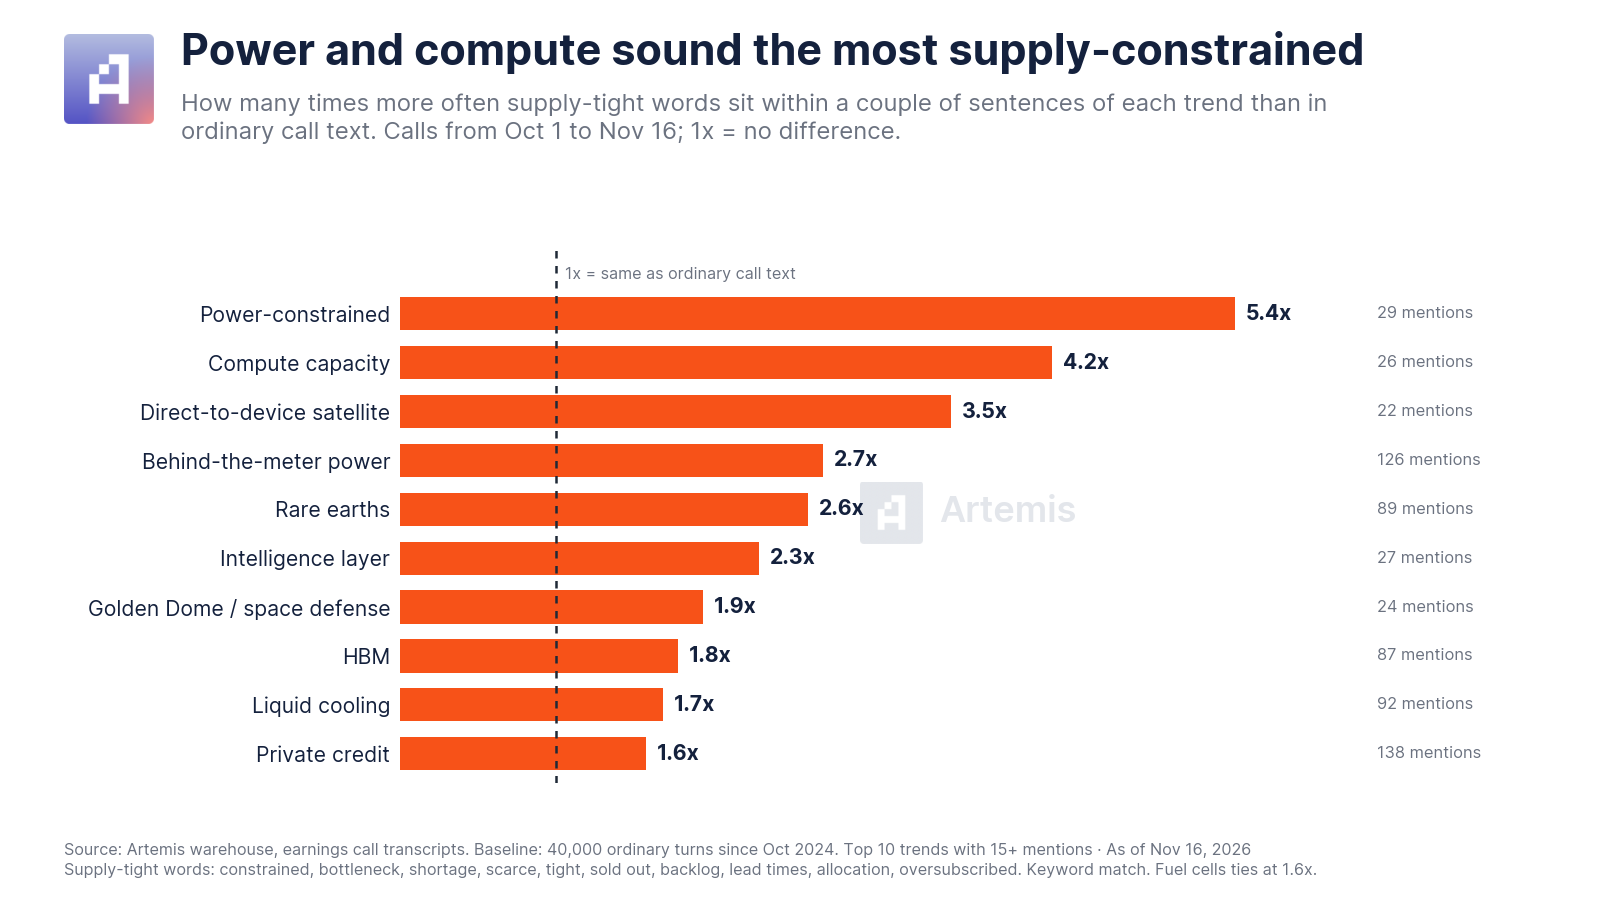
Side Chart - You’re Probably Sick of Bottlenecks
We analyzed calls from this past earnings season to find themes associated with words like ‘bottleneck’ and ‘constrained.’ The top theme: POWER.
Users Change the Channel: Netflix
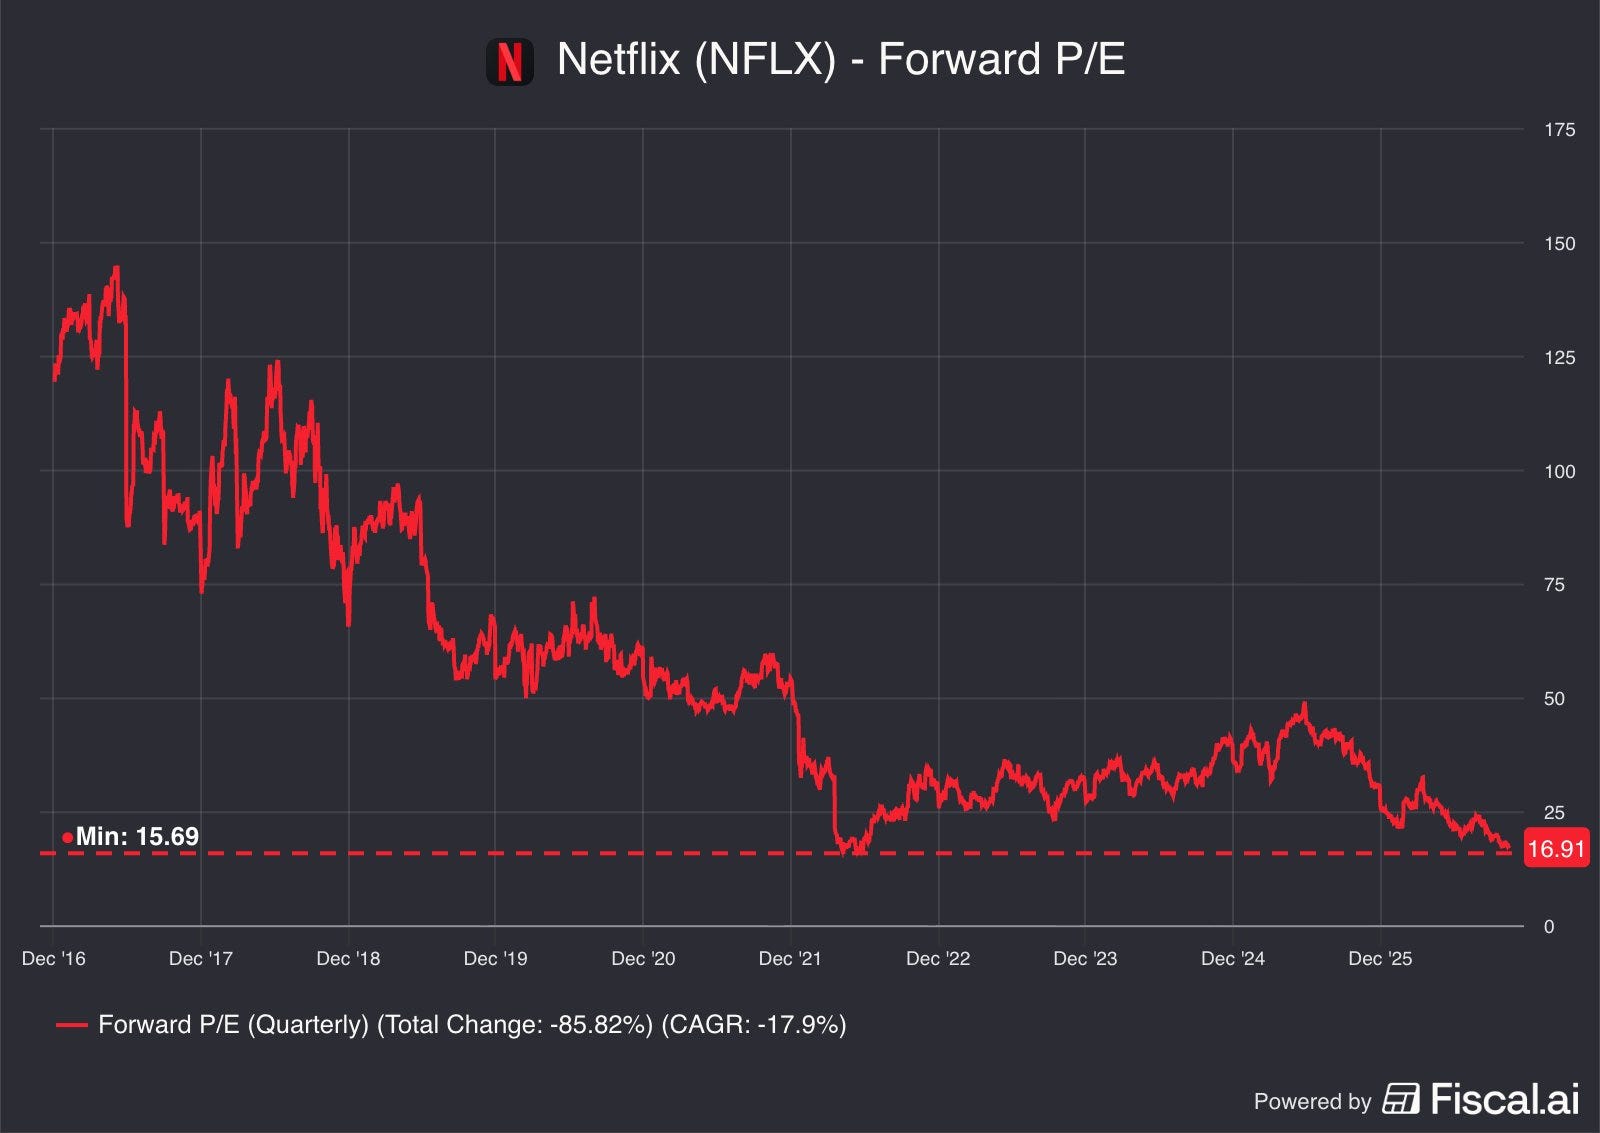
Netflix hit a 52-week low this week and is now below $60 a share, for the first time in two years. Netflix trades at historic forward P/E lows and is facing a whole series of challenges from staff reductions to management changes and insider selling. What’s going on?
The Lack of “Home Runs”
On Netflix’s most recent earnings call, Ted Sarandos, Netflix co-CEO, said
We had some really solid doubles and triples this year. But the other territories count on some of those titles being home runs so that they'll travel around the world.
Netflix parted ways with Bela Bajaria, its Chief Content Officer who was appointed the the role Jan 2023. Bajaria will be replaced by Peter Rice, who was formerly the chairman of Walt Disney Television. Rice was abruptly fired in 2022 and has been producing select television shows since then. Who said media stocks don’t have drama?!?
Slowing engagement
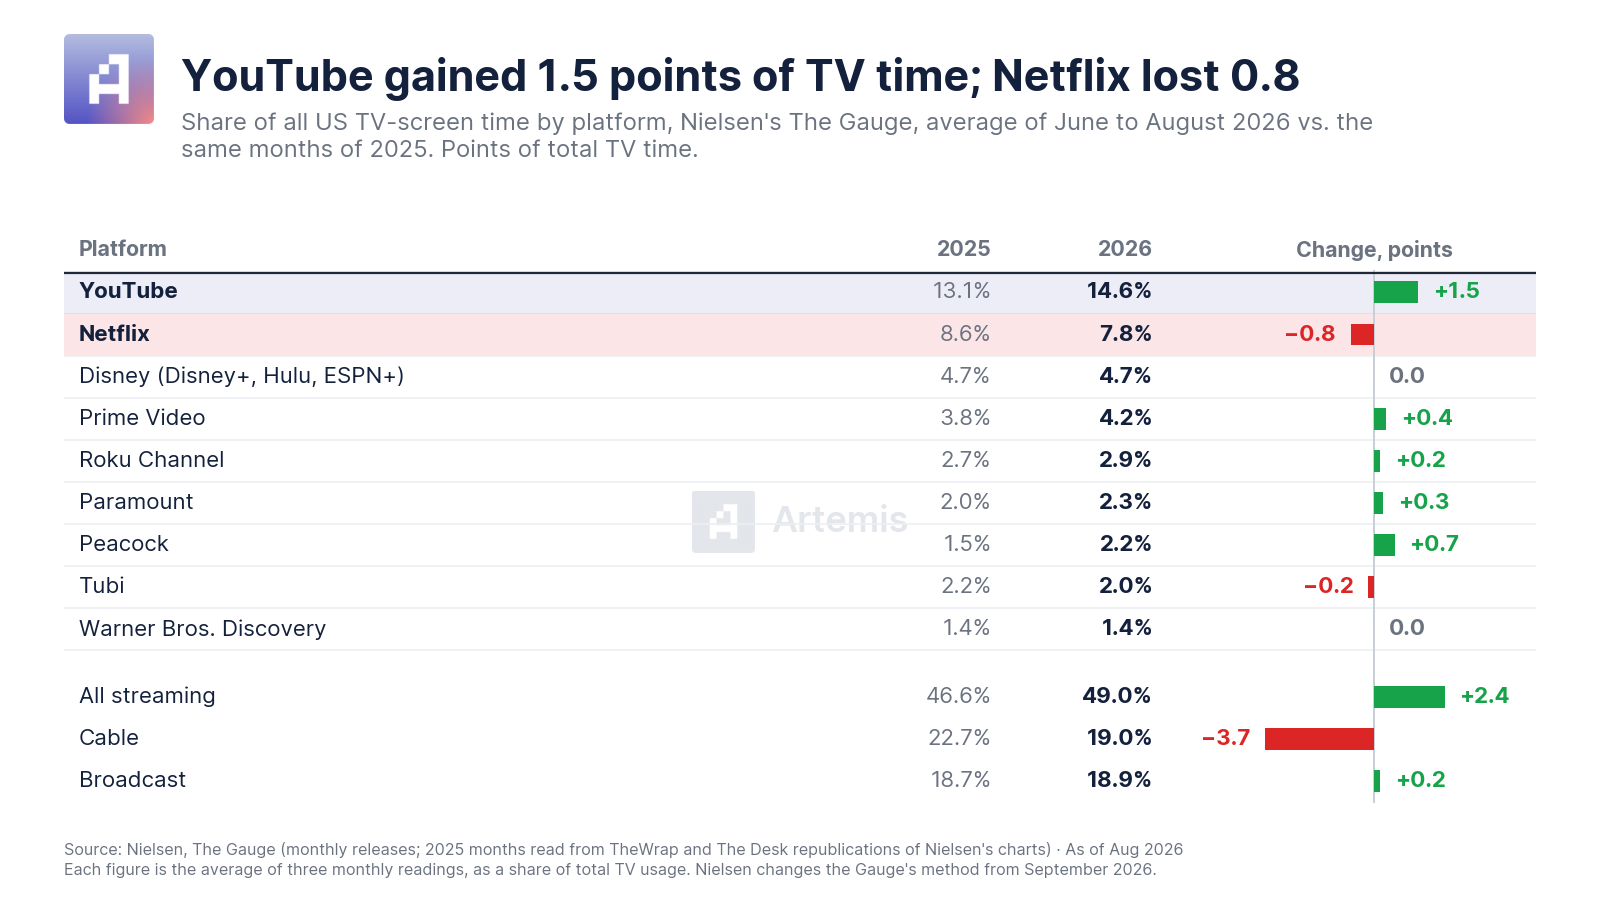
The CFO called hours growth “modest” and said, “we want to grow view hours faster. We’re not satisfied.” The rise in streaming services, YouTube and social media (TikTok, Instagram) have all put pressure on viewing hours for Netflix. Netflix’s share of viewing hours dropped from 2025 to 2026, with YouTube the largest gainer.
Slowing Revenue Growth
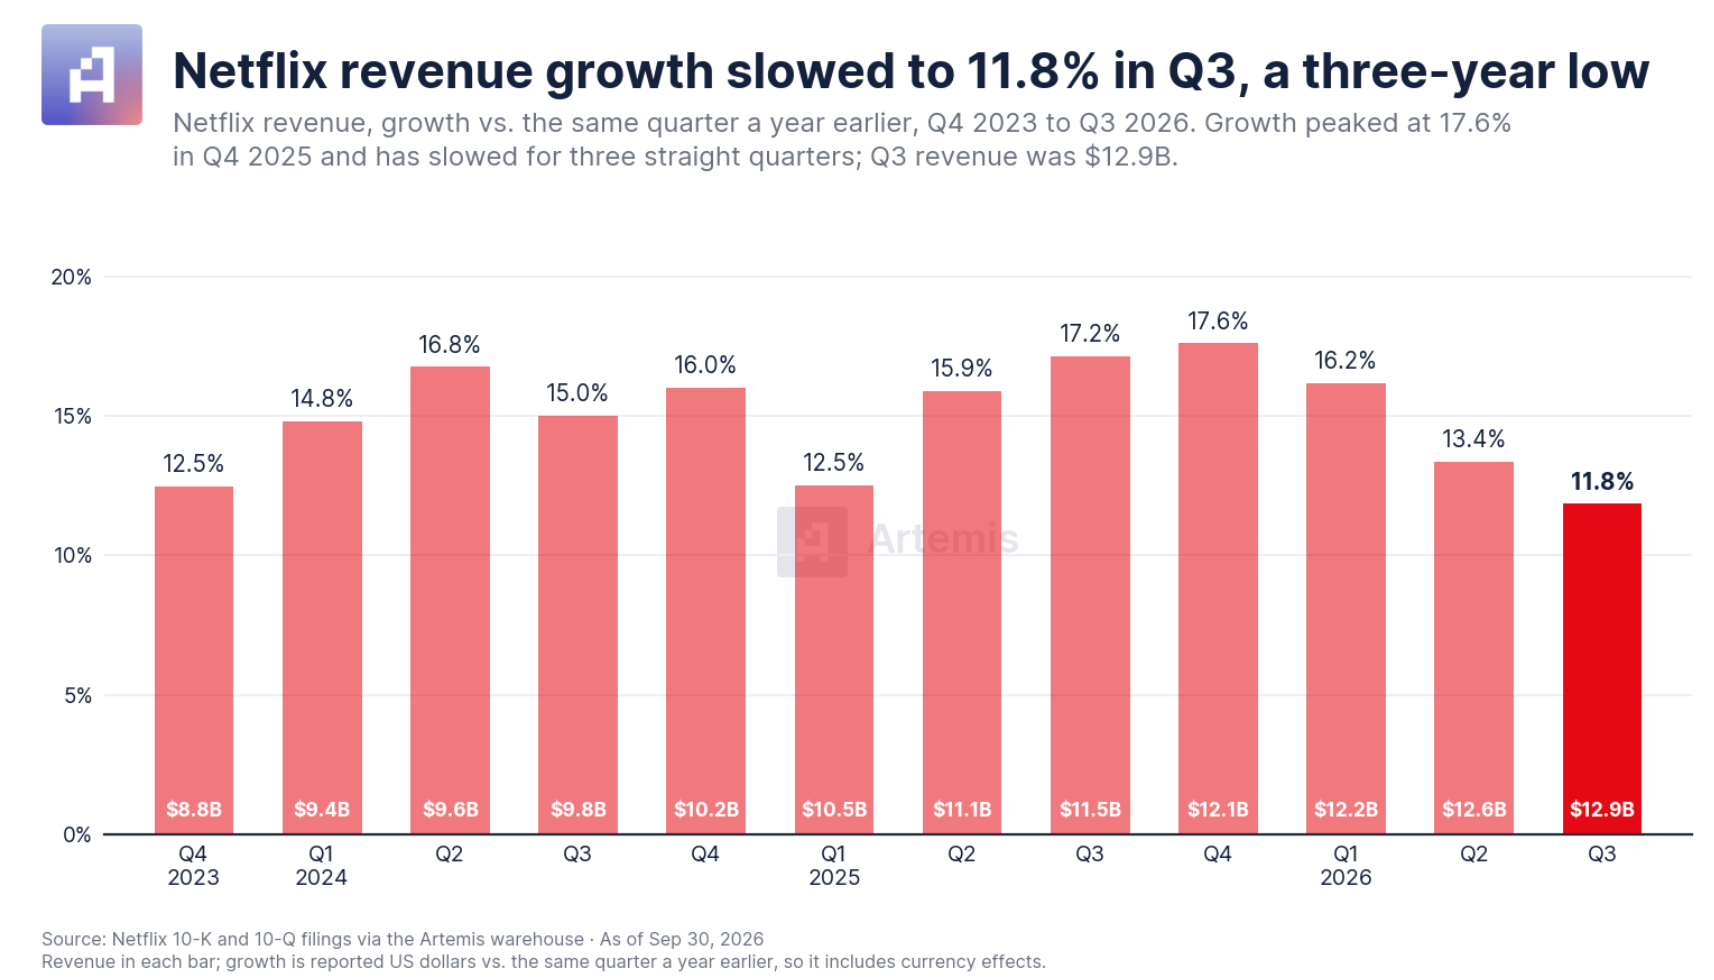
When asked if Netflix could deliver double-digit revenue growth for 2027, management responded it was not the right time to give full year 2027 guidance. The past quarter was the slowest Netflix grew revenues in the past three years and estimates for 2027 growth are in the 10% range.
Pershing Sees Value
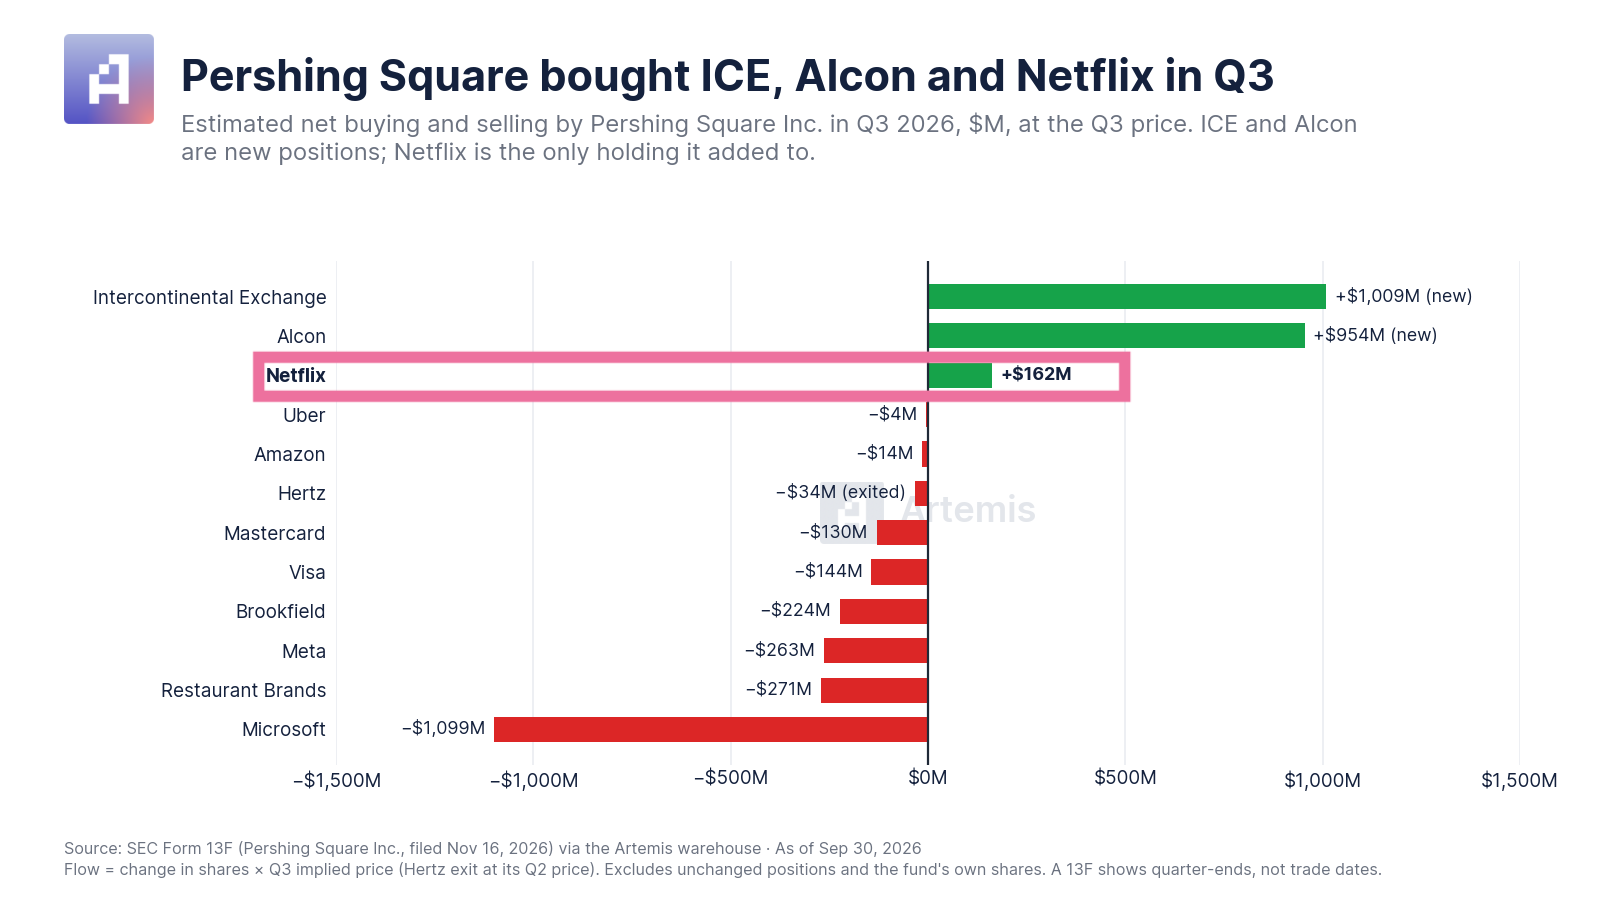
The depressed valuations have caught Bill Ackman’s attention. While Ackman has had an on/off relationship with Netflix (buying in 2022, only to sell quickly after), Ackman added to his Netflix position in the previous quarter. Here is Ackman on the most recent Equity Mates podcast talking about why he re-entered the position
“Then they [Netflix] disappointed people again more recently, or there were some concerns raised about the attention time that US subscribers are spending on Netflix, and the stock got cut in half. But, reassessed the situation: they've very successfully built a kind of an advertising model. They've really moved into clearly the number one position in the space. They've become a much more free cash flow generative business. So we think it's a lower risk, as good an opportunity here. And at 50% off versus where it was even a few months ago, we thought it was an attractive entry price”
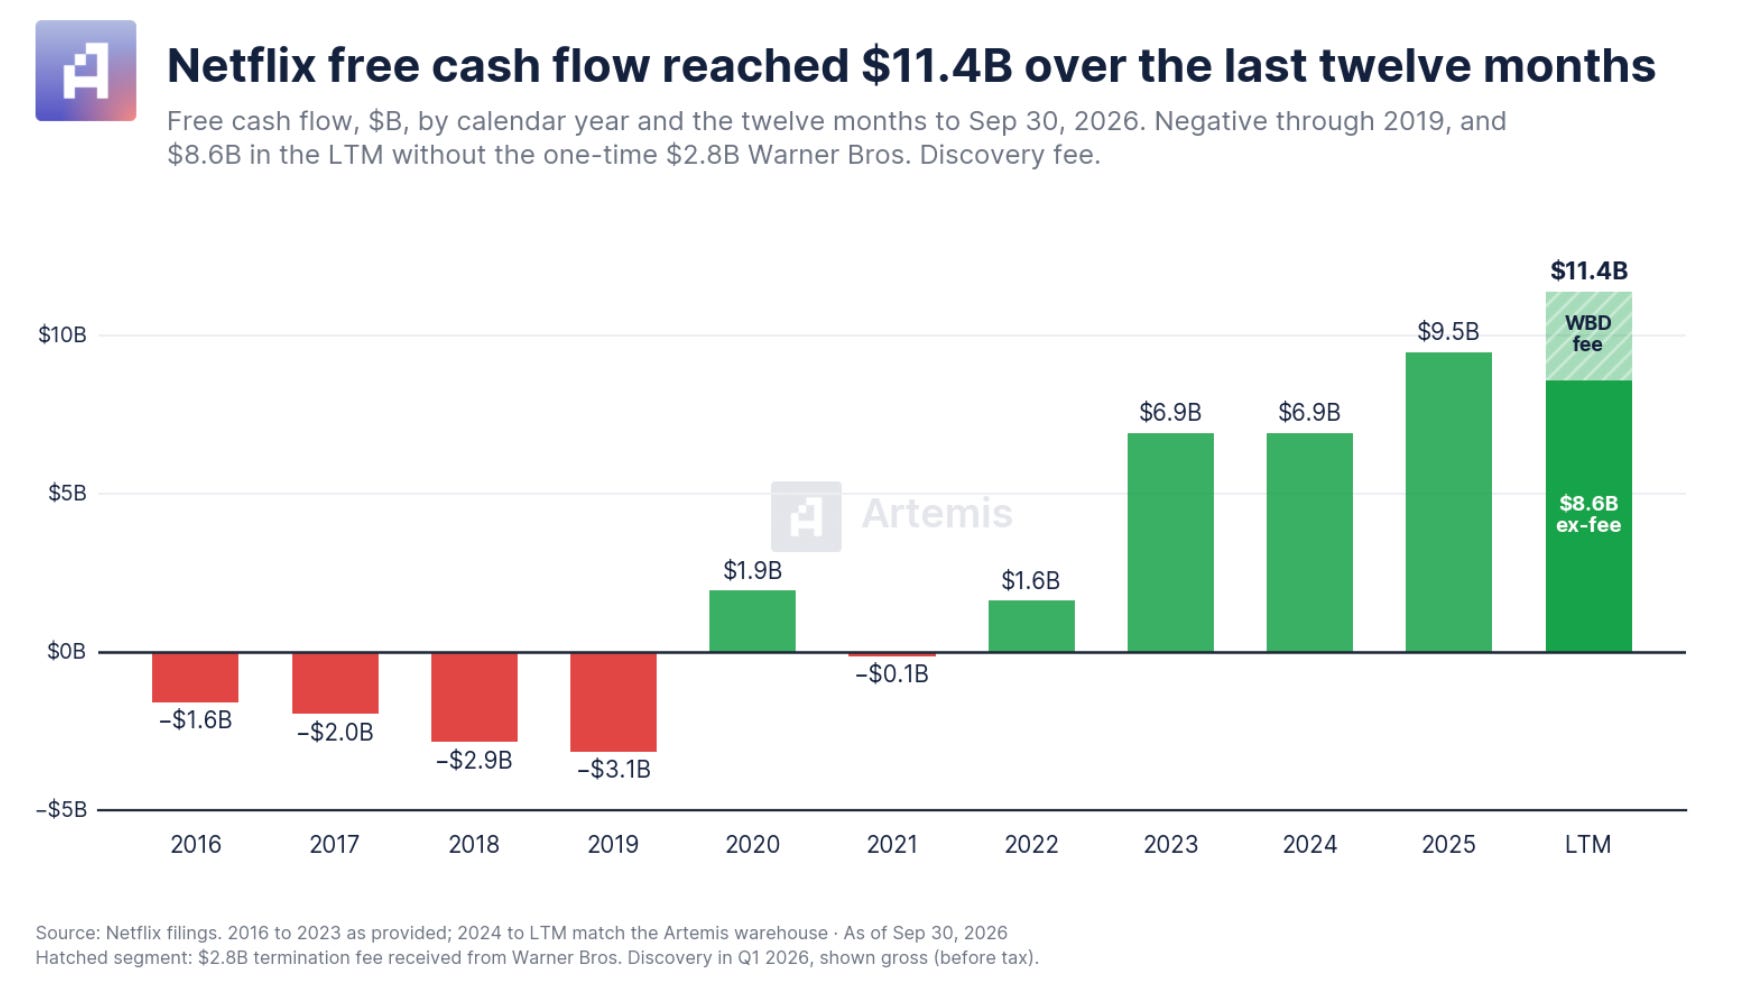
Pershing increased its Netflix stake by 18%, adding over 2 million shares from Q2 to Q3. Netflix was the largest addition of an existing position that Pershing had. Ackman is certainly right on the free cash flow point, and through the years Netflix has had a remarkable turn of free cash flow.
Can Netflix find another hit?
This post is published for informational and educational purposes only. Nothing here is investment, financial, legal, or tax advice, and nothing here is a recommendation or solicitation to buy, sell, or hold any security.
Conflicts of interest. I hold economic interests in Anthropic through SPVs, and Artemis Analytics holds economic interests in Anthropic directly and/or through pooled investment vehicles. We stand to benefit if Anthropic’s valuation rises, and we may buy or sell these interests at any time without updating this post.
Not an adviser. Neither I nor Artemis Analytics is a registered investment adviser or broker-dealer. I do not know your financial situation, objectives, or risk tolerance.